When you’re already struggling with debt, choosing the wrong settlement agency can genuinely make things worse — wasted fees, unrealistic promises, and a process that leaves you more confused than when you started. Before you hand over your documents or pay anything, you should know exactly what the agency actually does, how it charges, what it promises, and how it communicates with your lenders.
Here’s a simple principle worth holding onto as you evaluate your options: don’t choose an agency because it promises the biggest discount. Choose it because its process is transparent, realistic, and properly documented. Any agency worth working with — including one you’re evaluating right now — should hold up under this kind of scrutiny.
What Does a Debt Settlement Agency Actually Do?
A legitimate debt settlement agency typically:
- Assesses your overall financial situation
- Reviews your outstanding debts across lenders
- Helps you organise the documentation your case will need
- Communicates or coordinates with lenders, where properly authorised to do so
- Assists with the actual negotiation
- Explains the settlement terms in plain language
- Supports you through documentation and the steps that follow settlement
One thing worth being clear about upfront: no agency can guarantee that a lender will accept any particular settlement amount. The lender makes that decision, not the agency. What a good agency can genuinely offer is expertise, structure, and support through a process that’s often confusing and stressful to navigate alone.
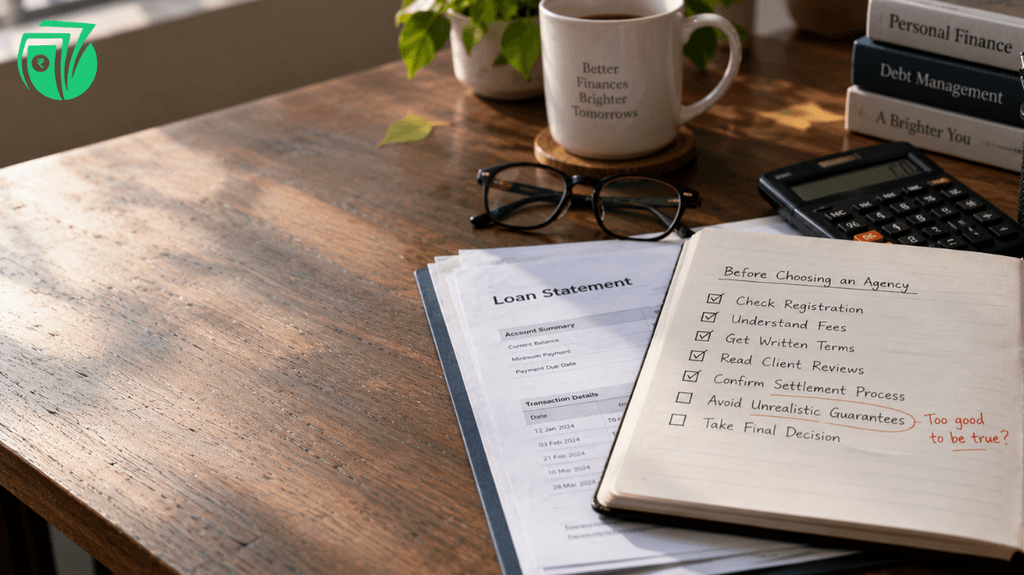
10 Things to Check Before Choosing a Debt Settlement Agency
1. Does the Agency Clearly Explain Its Process?
Look for a transparent walkthrough of what actually happens: Assessment → Strategy → Negotiation → Settlement Offer → Payment → Documentation.
Be cautious of any company that can’t clearly explain what happens after you sign up — vagueness here is often a sign of vagueness everywhere else too.
2. How Does the Agency Charge?
Get clarity on:
- Upfront fees
- Success-based fees
- Monthly charges
- Additional administrative charges
- Applicable taxes
- Cancellation and refund terms
Red flag: Unclear pricing, or fees that aren’t explained to you in writing before you commit.
3. Does It Promise a Guaranteed Settlement Percentage?
This deserves particular attention. Be wary of claims like “we’ll settle every loan at exactly 40%.”
Actual settlement outcomes depend on:
- The specific lender
- Your account status
- The outstanding amount
- Your individual circumstances
- How the negotiation unfolds
- The lender’s own internal decision
No agency should present a lender’s decision as guaranteed — because it genuinely isn’t theirs to guarantee.
4. Who Actually Negotiates With Your Lenders?
Ask directly:
- Who communicates with the lender on your behalf?
- Is there a dedicated relationship manager assigned to your case?
- Will you receive copies of important communications?
- How will settlement offers actually be communicated to you?
- Can you reach the agency when you need to, not just when they need something from you?
5. Does the Agency Explain the Credit-Score Consequences?
A responsible agency should clearly explain, without prompting, that settlement can negatively affect your credit history — and that “Settled” is a different status from “Closed.”
🚩 Red flag: An agency claiming that settlement will automatically improve your CIBIL score. This isn’t how settlement works, and it’s a sign the agency isn’t being straight with you.
6. Are Settlement Terms Provided in Writing?
Before any payment happens, confirm that the actual lender’s written settlement communication clearly states:
- Your account details
- The settlement amount
- The payment deadline
- Payment instructions
- The relevant terms
- How any remaining liability is treated
- The credit-reporting status that will follow
7. Does the Agency Help With Documentation?
A good process should clearly tell you what documents your case actually needs — not leave you guessing. This might include:
- Loan or credit card statements
- Income documents
- Bank statements
- Proof of hardship
- Previous correspondence with your lender
8. Does It Have Clear Customer Support?
Check for:
- Working, responsive customer-support channels
- Reasonable response times
- Actual availability of your assigned relationship manager
- A clear escalation process if something goes wrong
- A preference for written communication over vague verbal assurances
9. Can You Verify the Company’s Identity?
Before sharing any sensitive financial information, verify:
- The company’s legal business name
- Its registered office and contact details
- An official, functioning website
- Published terms and privacy policy
- Genuine customer-service details
- Relevant registrations or authorisations, where applicable
Don’t rely solely on a social media profile or WhatsApp message to establish that a company is legitimate — these are easy to fake and hard to verify independently.
10. Does It Explain Alternatives to Settlement?
This is genuinely one of the best tests of an agency’s credibility. A responsible agency should help you understand whether alternatives like:
- Continuing regular repayment
- Restructuring your existing loan
- Refinancing or consolidation, where appropriate
- Other lender-approved arrangements
might actually suit your situation better than settlement. If an agency pushes settlement immediately, without properly assessing your circumstances, that’s a real warning sign — settlement isn’t the right answer for everyone, and a good agency should be willing to say so.
Debt Settlement Agency Red Flags
A quick, scannable list of warning signs:
Guaranteed CIBIL improvement
Pressure to pay immediately
No written agreement provided
Unclear or shifting fee structure
Requests to pay into personal (not company) accounts
Refusal to share verifiable company details
Requests for unnecessary sensitive information
No explanation of credit consequences
Claims that they can “force” a bank to settle
If you notice more than one or two of these, it’s worth pausing and looking elsewhere.
Questions to Ask Before Signing Up
A copyable checklist to bring into any conversation with a prospective agency:
Before I enrol, I want to know:
- What exactly will you do for me?
- How are your fees calculated?
- Are there any additional charges I should know about?
- When do I have to pay, and under what conditions?
- Can you guarantee a specific settlement amount?
- Who negotiates with my lender directly?
- How will I receive settlement offers as they come in?
- What happens if my lender rejects the proposed offer?
- How will settlement affect my credit report?
- What happens after the settlement payment is made?
- What documentation will I actually receive?
- What happens if I want to leave the programme partway through?
A legitimate agency should be able to answer every one of these clearly, without hedging or redirecting.
How to Compare Two Debt Settlement Agencies
| Factor | Agency A | Agency B |
|---|---|---|
| Transparent fees | ✓ / ✗ | ✓ / ✗ |
| Written agreement | ✓ / ✗ | ✓ / ✗ |
| Explains CIBIL impact | ✓ / ✗ | ✓ / ✗ |
| No guaranteed settlement claims | ✓ / ✗ | ✓ / ✗ |
| Dedicated support | ✓ / ✗ | ✓ / ✗ |
| Explains alternatives | ✓ / ✗ | ✓ / ✗ |
| Clear documentation process | ✓ / ✗ | ✓ / ✗ |
| Verified company information | ✓ / ✗ | ✓ / ✗ |
Print or copy this table when you’re evaluating more than one option side by side — it makes the comparison a lot more concrete than relying on impressions from a sales call.
Agency vs Negotiating Directly With Your Bank
| Direct Negotiation | Debt Settlement Agency |
|---|---|
| You communicate directly with the lender | An agency may assist with lender communication |
| No agency fee | An agency may charge a service fee |
| You manage your own documentation | An agency may help organise documents |
| You handle negotiation yourself | Professional support may be available |
| More responsibility falls on you | Less administrative burden on you |
Using an agency isn’t mandatory — plenty of borrowers negotiate directly with their lender and do just fine. It’s worth honestly weighing whether the support an agency provides is worth its cost for your specific situation, rather than assuming professional help is automatically necessary.
What a Good Debt Settlement Agency Should Never Promise
No legitimate agency can guarantee that every lender will accept a specific settlement percentage. Beyond that, be cautious of any agency promising:
- Guaranteed debt reduction
- Guaranteed CIBIL recovery
- Guaranteed settlement approval
- A guaranteed timeline
- A guaranteed legal outcome
Genuine expertise shows up as honest expectation-setting, not confident guarantees about outcomes that ultimately rest with your lender.
Final Checklist — Before You Choose
Verify:
- Company identity
- Fee structure
- Written terms
- Scope of services
- Communication process
- Settlement documentation practices
- Credit implications, clearly explained
- Cancellation terms
- Customer support quality
- Whether alternatives are genuinely discussed
Avoid:
- Guarantees of any kind on settlement outcomes
- Pressure tactics to sign up or pay quickly
- Hidden or unclear charges
- Requests for payment to unverified or personal accounts
- Verbal-only promises with nothing in writing
Frequently Asked Questions
How do I choose a debt settlement agency?
Look for transparent fees, a clear written process, honest disclosure of credit-report consequences, no guaranteed outcomes, and a willingness to discuss alternatives to settlement before pushing you toward it.
Is it safe to use a debt settlement agency in India?
It can be, provided you verify the agency’s legitimacy, insist on written terms, and avoid any company making guarantees about settlement percentages or credit score improvements.
How much does a debt settlement agency charge?
Fee structures vary — some charge upfront, others on a success basis, and some combine both. Always get the complete fee structure in writing before signing up.
Can a debt settlement agency guarantee a settlement percentage?
No legitimate agency can guarantee this, since the final decision rests with the lender, not the agency. Treat any such guarantee as a red flag.
Will using a debt settlement agency affect my CIBIL score?
The settlement itself — not the agency you use — is what gets reported to credit bureaus, typically as “Settled.” A good agency should explain this clearly rather than downplay it.
What questions should I ask before hiring a debt settlement company?
Ask about their process, fee structure, who negotiates on your behalf, how offers are communicated, credit-report implications, and what happens if you want to exit the programme.
How can I verify whether a debt settlement agency is legitimate?
Check their legal business name, registered address, official website, published terms and privacy policy, and genuine customer-service channels — don’t rely on social media or informal messaging alone.
Can I negotiate a loan settlement without an agency?
Yes, many borrowers do this directly with their lender. Whether an agency’s support is worth the cost depends on your comfort with the process and your specific situation.
What documents should a debt settlement agency provide?
You should receive copies of key correspondence, the lender’s written settlement terms, and post-settlement documentation such as payment confirmation and any NOC or No Dues Certificate.
What are the warning signs of a debt settlement scam?
Guaranteed outcomes, pressure to pay immediately, requests to pay into personal accounts, refusal to share verifiable company details, and no written agreement are all significant warning signs.
Choosing the right support for your debt situation is a big decision — and it deserves the same scrutiny you’d apply to any major financial choice. If you’d like a transparent, honest conversation about your options before committing to anything, that’s exactly what a good starting point should look like.
👉 Get a free debt assessment with TrueSettle
👉 Talk to a debt counsellor about what approach fits your situation.