Short answer: Yes. Canara Bank does offer loan settlement. It runs One-Time Settlement (OTS) schemes for eligible borrowers, and it has an online e-OTS (Electronic One-Time Settlement) facility for small-value NPA accounts. But settlement is not automatic. The bank decides case by case, based on its current policy, your account status and how much you can realistically pay.
If you have missed EMIs on a Canara Bank loan and the recovery calls have started, this guide walks you through what OTS actually is, who usually qualifies, how to apply, what papers to keep ready and what settlement does to your CIBIL score. No jargon, no false promises.
Does Canara Bank Provide Loan Settlement?
Yes, and you don’t have to take anyone’s word for it. The bank says so in its own documents.
The official website lists an e-OTS facility, which lets eligible borrowers apply for settlement online.
The Annual Report 2024–25 states that the bank introduced e-OTS as an automated settlement package for small-value NPA accounts. It also mentions special OTS schemes for agriculture, education and MSME loans, along with other eligible small-value accounts.
A published special OTS notice describes a settlement opportunity for eligible NPA borrowers across MSME, agriculture, retail and other segments. Under that notice, borrowers could pay the settled amount in one lump sum, or, subject to scheme conditions, pay 10% to 25% upfront and clear the balance within 90 days.
One honest caution here. Scheme terms change, and old notices expire. Before you plan around any percentage or deadline, confirm with your branch whether that scheme is still open and whether your account fits it.
Is every borrower eligible?
No. Under the RBI’s stressed-assets directions for commercial banks issued in November 2025, a compromise settlement is a decision the bank takes using its own commercial judgement. Indian courts have also held, more than once, that no borrower can demand an OTS as a matter of right. So think of settlement as something you request and negotiate, not something you are owed.
What Is the Canara Bank One-Time Settlement (OTS) Scheme?
A One-Time Settlement is a compromise. You can’t repay the full outstanding, so the bank agrees to accept a lower amount and close the account. Once you pay the agreed sum on time, the bank stops chasing you for the rest.
People often mix this up with two other things.
Settlement is not a waiver. A waiver usually comes from a government scheme, where dues are written off for a group of borrowers. In a settlement, you still pay a negotiated amount yourself, and the bank reports the account as “settled”.
Settlement is not restructuring. Restructuring keeps the loan alive. The bank may stretch the tenure, lower the EMI or give a short moratorium, and you eventually repay the full amount. Settlement ends the loan for less than what you owed.
If your income has dipped only for a while, restructuring may protect your credit record better. If the gap is permanent and the debt keeps growing, settlement is usually the more realistic path.
Who Is Eligible for Canara Bank Loan Settlement?
There’s no single public checklist that covers every case. Each scheme sets its own rules. In practice, the bank looks at a few common things.
- NPA status. Canara Bank’s published OTS schemes are built for NPA accounts, meaning loans that have stayed overdue past the regulatory limit. A borrower who has missed one EMI is unlikely to be offered OTS straight away.
- Genuine financial hardship. Job loss, a business shutdown, a serious illness or a death in the family carries weight when you can show proof.
- What you can actually pay. The bank wants a realistic offer it can collect, not a number that falls apart after the first instalment.
- Loan category. Some special schemes cover only certain segments, such as agriculture, MSME or education loans.
- The scheme in force at the time. Cut-off dates, outstanding limits and payment windows change with each scheme.
If your account doesn’t fit a running scheme, you can still write to the branch with a settlement proposal. The bank may consider it under its general recovery policy, though nothing guarantees approval.
Which Loans Can Be Considered for Canara Bank OTS?
Different loans get treated differently. Here is a realistic picture of each.
| Loan type | What to expect |
|---|---|
| Personal loan | Can be discussed once the account is in default and you can show hardship. Being unsecured, the bank relies more on your proof and your offer. |
| Agricultural loan | Named in the bank’s special OTS schemes. Check whether a scheme is currently open for your account. |
| MSME / business loan | Also covered by special OTS schemes. Business accounts usually need financial statements and proof of losses. |
| Education loan | Mentioned in the bank’s special OTS schemes. Co-borrower and guarantor details matter here. |
| Credit card dues | Settlement is often possible, but don’t assume a published scheme covers cards. Ask the bank directly. |
| Home loan / loan against property | Possible, but harder. The bank holds security and can recover through it, so offers are judged against the property’s value. |
No single scheme covers every loan type. Always ask the branch which scheme, if any, applies to your account.
What Is Canara Bank e-OTS and How Does It Work?
This is the part most settlement guides skip, and it can save you a lot of running around.
e-OTS stands for Electronic One-Time Settlement. According to the bank’s Annual Report 2024–25, it is an automated settlement package for small-value NPA accounts. In simple terms, if your outstanding is small and your account is already an NPA, you may be able to check eligibility and apply for settlement online instead of starting with a branch visit.
| e-OTS | Branch-assisted OTS | |
|---|---|---|
| Who it’s for | Small-value NPA accounts | Accounts that need individual review, or fall outside e-OTS limits |
| How you apply | Online, through the bank’s official website | Written request at the branch or recovery office |
| Terms | Set by the automated package | Negotiated case by case |
| Best for | Smaller dues and borrowers who want a quicker process | Larger dues, secured loans or complex cases |
How to check if e-OTS is open to you: go to Canara Bank’s official website and look for the e-OTS option, or ask your home branch. Use only official bank channels. Never share OTPs or pay anyone who claims to be an “OTS agent” outside the bank’s own payment system.
How to Apply for Canara Bank Loan Settlement
Take it one step at a time. Rushing usually means a weaker offer or a missed detail.
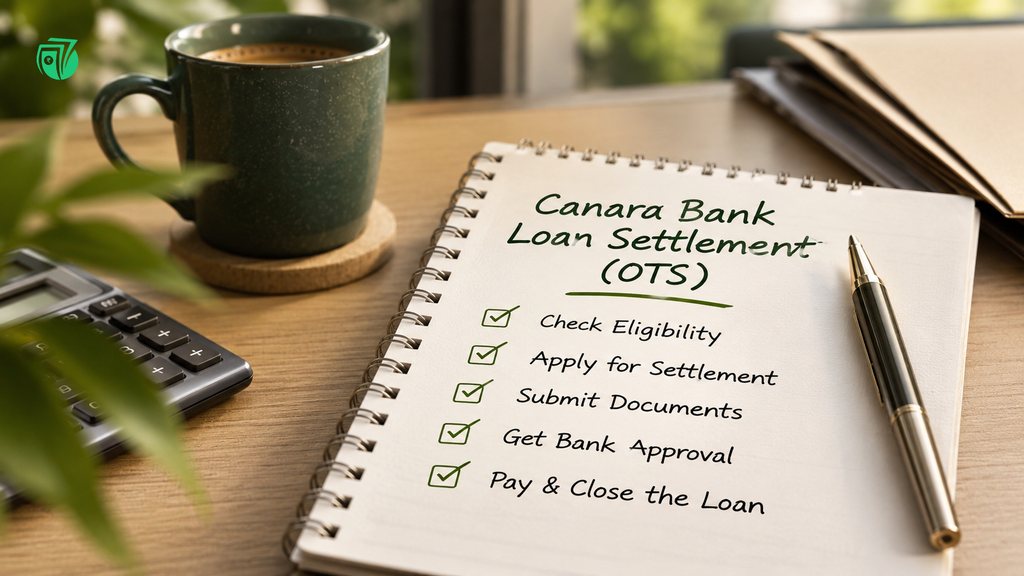
- Know your exact dues. Ask the branch for a statement showing principal, interest and penal charges separately.
- Check for a running scheme. See whether e-OTS or a special OTS scheme applies to your loan.
- Talk to the right desk. That’s your home branch or the recovery department handling your account.
- Put your request in writing. Explain what went wrong, what you can pay and how soon. Keep a stamped acknowledgement copy.
- Attach hardship proof. Termination letter, medical bills, business loss records, whatever applies to you.
- Let the bank assess it. There’s no fixed timeline. The bank may ask follow-up questions or counter your offer.
- Read the offer letter carefully. Check the amount, the due dates and what happens if you miss a payment.
- Pay only as per the letter. Use official bank channels, never cash to an individual, and keep every receipt.
- Collect your closure papers. Get the settlement confirmation and No Dues Certificate, and release any security or documents the bank holds.
A real-life example: Ravi, a sales executive in Lucknow, lost his job in 2024 with about ₹3.2 lakh left on a Canara Bank personal loan. After eight months of missed EMIs, the account turned NPA. He wrote to his branch with his termination letter and six months of bank statements, and proposed a lump-sum payment funded partly by his family. The bank came back with a counter-offer. He paid on time and collected his No Dues Certificate. (Illustrative example. Every case and outcome is different.)
Documents Required for Canara Bank Loan Settlement
Keep these ready before you approach the bank. A complete file shows you’re serious and speeds things up.
- Loan account number and sanction letter
- PAN, Aadhaar and address proof
- Bank statements for the last 6 to 12 months
- Income proof, such as salary slips, ITRs or business records
- Proof of hardship: termination letter, medical records, or evidence of business losses
- Copies of any recovery notices or legal notices you’ve received
The bank may ask for more depending on the loan type and the scheme.
How Much Does Canara Bank Accept in Loan Settlement?
There is no fixed percentage, and anyone promising one is guessing. The final number depends on:
- Outstanding principal and interest. Most negotiation happens around interest and penal charges, not the principal.
- Penal charges that have built up after default.
- Security or collateral. If the bank can recover through a property, it will expect more.
- How old the default is and what recovery steps are already underway.
- Your repayment capacity. A lump sum you can pay now usually carries more weight than a long instalment plan.
- The rules of the scheme in force when you apply.
A practical tip: make an offer you can actually pay on the dates in the letter. A missed settlement instalment can cancel the deal, and you may lose the concession.
What Happens to Your CIBIL Score After Canara Bank Loan Settlement?
Settlement brings relief, but it leaves a mark. When you repay less than the full amount, the account is usually reported to credit bureaus as “Settled”, not “Closed”.
- “Closed” means you repaid everything. Lenders see this as positive.
- “Settled” means the lender accepted less than it was owed. Lenders see this as a risk signal.
The exact effect on your score depends on your whole credit history, so be wary of anyone quoting a fixed point drop. What’s certain is that a settled account can make new loans and credit cards harder to get, or more expensive, for some time.
Rebuilding after settlement:
- Check your CIBIL report a few weeks after paying, and confirm the account shows the right status.
- Pay every remaining EMI and card bill on time.
- Keep credit card usage low.
- Consider a secured credit card against a fixed deposit to rebuild a clean repayment record.
- If you later have the means, ask the bank whether paying the remaining balance can change the status from “Settled” to “Closed”.
Can Canara Bank Take Legal Action After Loan Default?
Yes. Defaulting doesn’t put recovery on hold, and asking for settlement doesn’t either.
- Recovery notices. The bank will usually send reminders and formal notices first.
- Recovery proceedings. For larger dues, the bank can approach the Debt Recovery Tribunal or other forums.
- SARFAESI action. For eligible secured loans, the bank can take possession of the mortgaged property under the SARFAESI Act without going to court first.
A settlement offer does not automatically stop proceedings already underway. Any case or SARFAESI action has to be addressed separately, ideally in writing as part of the settlement terms.
Above all, never ignore a legal notice. Reply on time, keep copies, and get advice if you’re unsure what it means.
What If Canara Bank Rejects Your OTS Request?
A rejection isn’t always the end. It often means the offer, the timing or the paperwork didn’t work.
- Ask for the reason in writing, if the bank is willing to share it.
- Revise your offer if you can arrange more funds or a shorter payment window.
- Strengthen your documents. Missing hardship proof is a common weak point.
- Explore restructuring if your income is likely to recover.
- Wait for a fresh scheme. Banks launch new OTS schemes from time to time, and your account may qualify later.
Loan Settlement vs Loan Restructuring vs Full Repayment
| Loan settlement (OTS) | Loan restructuring | Full repayment | |
|---|---|---|---|
| Amount you pay | Less than total dues | Full dues, spread out | Full dues |
| Loan status after | Ends | Continues with new terms | Ends |
| Credit report status | Usually “Settled” | Shows restructuring | “Closed” |
| Effect on future credit | Negative for some time | Milder than settlement | Positive |
| Best suited for | Permanent loss of income | Temporary cash crunch | Borrowers who can afford it |
How TrueSettle Can Help With Canara Bank Loan Settlement
Dealing with recovery calls and bank paperwork while you’re under financial stress is exhausting. TrueSettle helps you approach it calmly and in the right order.
- Understanding your situation. We look at all your debts, not just the Canara Bank loan.
- Reviewing your options. Settlement, restructuring or a repayment plan, whichever fits your case.
- Preparing your documents so your request is clear and complete.
- Guidance during lender discussions, so you know what to say and what to get in writing.
- Explaining the consequences, including the CIBIL impact, before you commit.
We don’t promise a fixed settlement amount, because no honest adviser can. What we do promise is a clear plan and straight answers.
Struggling with a Canara Bank loan? Book a free consultation with TrueSettle and understand your options today.
Related reading: our guides to SBI loan settlement, HDFC Bank loan settlement, ICICI Bank loan settlement, Axis Bank loan settlement, the difference between loan settlement and loan waiver, and how to rebuild your CIBIL score after settlement. (Add internal links before publishing.)
Frequently Asked Questions About Canara Bank Loan Settlement
1. Does Canara Bank provide loan settlement? Yes. Canara Bank provides One-Time Settlement (OTS) options for eligible borrowers under its applicable settlement schemes. The bank also has an Electronic One-Time Settlement facility for certain small-value NPA accounts. Approval depends on the bank’s prevailing policy and account eligibility.
2. What is the Canara Bank OTS scheme? The Canara Bank One-Time Settlement scheme allows eligible borrowers to negotiate a settlement of outstanding dues under the bank’s applicable policy. The agreed amount and payment conditions are determined by the bank.
3. How can I apply for Canara Bank loan settlement? Borrowers can approach their Canara Bank branch or the relevant recovery department, enquire about the applicable OTS scheme, submit a written request and provide supporting financial documents. The bank reviews the request before deciding whether to approve settlement.
4. Does Canara Bank offer online OTS? Canara Bank has introduced an Electronic One-Time Settlement facility for eligible small-value NPA accounts. Borrowers should check the official bank website for current availability and eligibility.
5. Does loan settlement affect my CIBIL score? Yes. A loan settled for less than the full outstanding amount may be reported as Settled rather than Closed. This can negatively affect your credit profile and future borrowing opportunities.
6. Is Canara Bank loan settlement guaranteed? No. Loan settlement is subject to Canara Bank’s applicable policy, eligibility conditions and approval. Borrowers cannot demand settlement as an automatic right.
7. What documents are required for Canara Bank OTS? Documents may include loan account details, identity proof, bank statements, income proof and supporting evidence of financial hardship. Additional documents may be requested by the bank.
8. Does Canara Bank settle credit card dues? Credit card dues can often be discussed for settlement after default, but published OTS schemes may not cover them. Confirm directly with the bank.
9. Will Canara Bank issue an NOC after settlement? Once you pay the full settled amount as per the offer letter, ask for a settlement confirmation and No Dues Certificate. Don’t consider the matter closed without them.
10. Can I get another loan after settling a Canara Bank loan? It’s possible, but harder for a while. Lenders will see the “Settled” status, so focus on rebuilding a clean repayment record first.
Final Word
Canara Bank does provide loan settlement, and its e-OTS facility makes the first step easier for small-value NPA accounts. Go in prepared: know your dues, keep your documents ready, make an offer you can honour, and get every term in writing.
Disclaimer: This article is for general information only and is not legal or financial advice. Scheme terms, eligibility and timelines are set by Canara Bank and can change. Confirm current details with the bank before acting.
Sources
- Canara Bank official website – e-OTS facility
- Canara Bank Annual Report 2024–25 – e-OTS and special OTS schemes
- Canara Bank special OTS scheme notice – published OTS terms
- RBI (Commercial Banks – Resolution of Stressed Assets) Directions, 2025 – regulatory framework
- TransUnion CIBIL – Impact of settled status – credit report effects