Loan Settlement Process in Hindi को समझना उन borrowers के लिए ज़रूरी है जिन्हें EMI चुकाने में लगातार मुश्किल हो रही है। अगर loan का outstanding amount बढ़ता जा रहा है, तो शायद आपने “loan settlement” के बारे में सुना होगा। लेकिन असल में यह प्रक्रिया कैसे काम करती है, इसके लिए क्या-क्या documents चाहिए, और settlement के बाद आपके CIBIL score पर क्या असर पड़ता है — इन सब सवालों के जवाब इस guide में आसान हिंदी में समझाए गए हैं।
लोन सेटलमेंट क्या है? — Loan Settlement Kya Hai?
Loan settlement एक ऐसी व्यवस्था है जिसमें lender (बैंक या NBFC) borrower से पूरी outstanding राशि लेने के बजाय, एक negotiated यानी कम राशि को accept कर लेता है, ताकि account को full-and-final तरीके से बंद किया जा सके।
इसे समझने के लिए कुछ ज़रूरी बातें:
- जब EMI चुकाना मुश्किल हो जाता है और financial hardship genuine हो, तो borrower lender से बातचीत कर सकता है।
- Settlement में तय की गई राशि, original outstanding amount से कम होती है।
- यह resolution उन्हीं शर्तों के तहत मान्य होता है जो दोनों पक्षों के बीच agree हुई हों।
- इस तरह की settlement को अक्सर One-Time Settlement (OTS) भी कहा जाता है।
यहाँ एक बात साफ़ समझ लेना ज़रूरी है — loan settlement, loan closure से अलग है। Closure में आप पूरी राशि चुकाते हैं, जबकि settlement में lender एक कम राशि accept करके account को resolve करता है।
लोन सेटलमेंट कब किया जा सकता है?
Settlement हर किसी के लिए automatically उपलब्ध नहीं होता। आमतौर पर यह तब considered किया जाता है जब:
- Borrower genuine financial hardship से गुज़र रहा हो — जैसे job loss, medical emergency, या income में अचानक कमी।
- लंबे समय से EMI चुकाने में दिक्कत हो रही हो, और situation temporary न लगे।
- Hardship को support करने वाले documents मौजूद हों।
- Lender की internal policy settlement की अनुमति देती हो।
यह ज़रूरी नहीं कि हर borrower को settlement का option मिले — यह पूरी तरह lender के assessment और account की स्थिति पर निर्भर करता है।
Loan Settlement Process — स्टेप-बाय-स्टेप
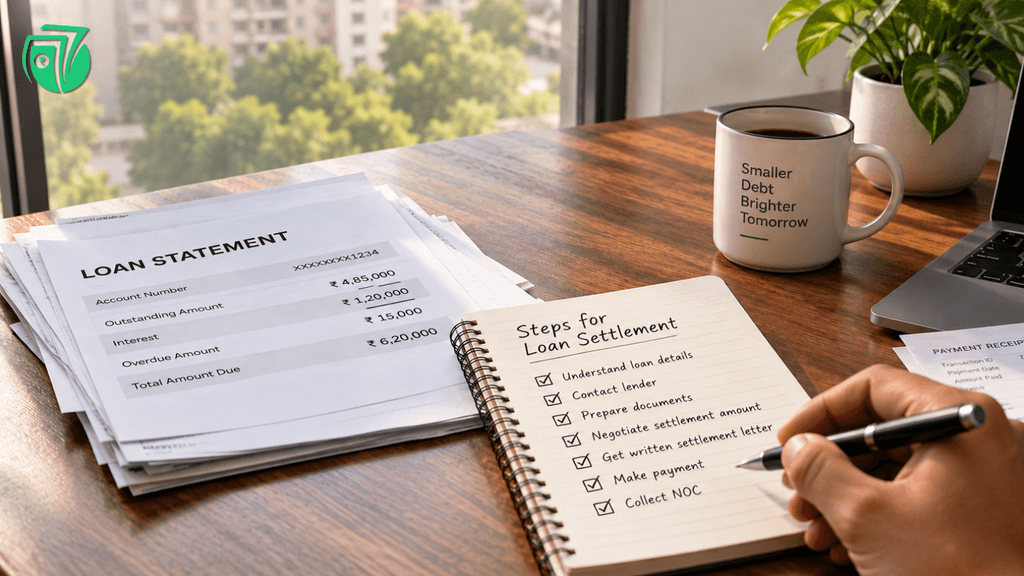
Step 1: अपना पूरा Loan हिसाब समझें
Negotiation शुरू करने से पहले, अपने loan की पूरी जानकारी clear रखें:
- Total outstanding amount
- Principal (मूल राशि)
- Interest amount
- Applicable charges (late fees, penalty आदि)
- Overdue amount
- Current EMI
बिना सही numbers जाने बातचीत करना, आपकी negotiation position को कमज़ोर कर सकता है।
Step 2: Bank/Lender से Contact करें
अपनी financial difficulty के बारे में lender के सही department — जैसे collections team या customer care — से संपर्क करें। जितनी जल्दी आप अपनी situation communicate करेंगे, negotiation के लिए उतनी ही ज़्यादा flexibility मिलने की संभावना रहती है।
Step 3: जरूरी Documents तैयार करें
Negotiation को मज़बूती देने के लिए ये documents तैयार रखें:
- Identity documents (Aadhaar, PAN)
- Loan/account statement
- Bank statements
- Income proof
- Financial hardship को support करने वाले documents
- Lender के साथ हुई पुरानी बातचीत/correspondence
Step 4: Settlement Amount पर Negotiation करें
Lender आमतौर पर आपकी repayment capacity का assessment करता है — यानी आप realistically कितनी राशि चुका सकते हैं। सही documentation इस negotiation को support करती है।
एक बात ध्यान रखें: कोई fixed या universal settlement percentage नहीं होता। हर case अलग होता है, और final amount आपकी specific स्थिति, account status और lender की policy पर निर्भर करता है।
Step 5: Written Settlement Letter लें
यह सबसे ज़रूरी step है:
लिखित settlement terms मिलने से पहले payment न करें।
Settlement letter में ये सारी details clearly mention होनी चाहिए:
- Account number
- Outstanding amount
- Settlement amount
- Payment deadline
- Payment method
- Resolution की शर्तें
- Credit-reporting status (यानी account किस तरह report होगा)
Verbal बातचीत पर भरोसा करके payment करना risky हो सकता है — अगर बाद में कोई dispute हो, तो written proof के बिना आपके पास कुछ नहीं बचता।
Step 6: Payment करें और Documents संभालकर रखें
- हमेशा lender के authorised payment channel का इस्तेमाल करें।
- Agreed deadline को follow करें।
- Payment receipt ज़रूर संभालकर रखें।
- Payment के बाद NOC (No Objection Certificate) या No Dues Certificate ज़रूर लें, जहाँ applicable हो।
Loan Settlement के लिए कौन-कौन से Documents चाहिए?
| Document | क्यों जरूरी हो सकता है? |
|---|---|
| Aadhaar/PAN | Identity verification के लिए |
| Loan statement | Outstanding amount verify करने के लिए |
| Bank statements | Financial position दिखाने के लिए |
| Salary/income proof | Repayment capacity समझने के लिए |
| Job-loss/medical documents | Financial hardship support करने के लिए |
| Previous bank communication | Account history के लिए |
Loan Settlement के बाद क्या होता है?
Payment complete होने के बाद कुछ ज़रूरी steps होते हैं:
- Lender से payment confirmation लें।
- NOC/No Dues documentation collect करें।
- Account की status और reporting को verify करें।
- समझें कि इसका credit report पर क्या असर पड़ेगा।
- Future में credit rebuild करने की दिशा में काम शुरू करें — जैसे समय पर अन्य payments करना, credit utilisation कम रखना।
Settlement एक resolution है, लेकिन इसके बाद credit profile को दोबारा मज़बूत बनाना एक अलग, धीरे-धीरे होने वाला process है।
Loan Settlement का CIBIL Score पर क्या असर पड़ता है?
यह समझना बहुत ज़रूरी है:
Closed — जब आप loan की पूरी राशि, agreed terms के अनुसार चुका देते हैं।
Settled — जब lender ने एक negotiated राशि accept की हो, जो originally due amount से कम थी।
दोनों status credit report पर अलग तरह से दिखते हैं, और lenders इन्हें अलग नज़रिए से देखते हैं। यह कहना सही नहीं होगा कि settlement से आपका score कितने points गिरेगा, या कितने समय में recover होगा — यह हर borrower और हर lender के हिसाब से अलग हो सकता है। लेकिन इतना ज़रूर समझ लें कि settled account, closed account जैसा credit signal नहीं देता।
Loan Settlement और Loan Closure में क्या अंतर है?
| Loan Closure | Loan Settlement |
|---|---|
| पूरी outstanding राशि चुकाई जाती है | Agreed reduced amount accept किया जा सकता है |
| Account पूरी तरह repaid के रूप में report होता है | Account “Settled” के रूप में report हो सकता है |
| Credit history के लिए आमतौर पर बेहतर माना जाता है | Credit history पर negative असर हो सकता है |
Loan Settlement करते समय इन गलतियों से बचें
- बिना written settlement letter payment करना
- Verbal promise पर भरोसा करना
- Payment deadline miss करना
- Unauthorised account/channel में पैसा भेजना
- NOC/No Dues document न लेना
- CIBIL impact को ignore करना
- यह मान लेना कि हर borrower को समान settlement मिलेगा
क्या Loan Settlement आपके लिए सही विकल्प है?
Settlement हमेशा पहला या सबसे सही option नहीं होता। आपकी situation के हिसाब से, ये options भी consider किए जा सकते हैं:
- EMI restructuring
- Tenure modification
- Refinancing
- अन्य repayment arrangements
सही option आपकी affordability और lender की terms पर निर्भर करता है। इसलिए किसी भी फैसले से पहले अपनी पूरी financial situation को ध्यान से समझना ज़रूरी है।
Frequently Asked Questions — अक्सर पूछे जाने वाले सवाल
लोन सेटलमेंट क्या होता है?
Loan settlement वह प्रक्रिया है जिसमें lender, borrower से पूरी outstanding राशि लेने के बजाय एक negotiated, कम राशि accept करके account को resolve करता है।
लोन सेटलमेंट कैसे करें?
सबसे पहले अपना पूरा outstanding हिसाब समझें, lender से contact करें, ज़रूरी documents तैयार करें, settlement amount पर negotiate करें, written terms लें, और फिर payment करें।
क्या personal loan settle किया जा सकता है?
हाँ, कई मामलों में personal loan settle किया जा सकता है, बशर्ते borrower genuine financial hardship दिखा सके और lender उसे approve करे।
लोन सेटलमेंट के लिए कौन से documents चाहिए?
Identity proof (Aadhaar/PAN), loan statement, bank statements, income proof, और financial hardship को support करने वाले documents आमतौर पर चाहिए होते हैं।
क्या loan settlement legal है?
हाँ, यह lender और borrower के बीच एक कानूनी तौर पर मान्य agreement होता है, बशर्ते इसे properly document किया जाए।
लोन सेटलमेंट का CIBIL score पर क्या असर होता है?
Settled account को “Closed” account से अलग तरीके से report किया जाता है, और यह आमतौर पर credit score और future borrowing को प्रभावित करता है। सटीक असर हर case में अलग हो सकता है।
Settlement के बाद NOC क्यों जरूरी है?
NOC यह written proof होता है कि आपकी कोई outstanding liability नहीं बची है। इसे भविष्य में किसी भी dispute से बचने के लिए संभालकर रखना चाहिए।
क्या bank settlement amount कम कर सकता है?
यह lender के assessment, आपकी hardship documentation, और repayment capacity पर निर्भर करता है। कोई fixed या guaranteed percentage नहीं होता।
क्या loan settlement के बाद दोबारा loan मिल सकता है?
समय के साथ और responsible financial behaviour के ज़रिए, credit profile दोबारा बेहतर हो सकती है, जिससे भविष्य में loan मिलने की संभावना बढ़ती है। लेकिन यह guaranteed नहीं होता और समय लगता है।
Loan settlement और loan closure में क्या difference है?
Closure में पूरी राशि चुकाई जाती है और account “Closed” report होता है। Settlement में एक कम राशि accept की जाती है और account “Settled” के रूप में report होता है, जिसका credit history पर अलग असर होता है।
अगर आप अपनी loan repayment को लेकर परेशान हैं और सही रास्ता तय नहीं कर पा रहे, तो पहले अपनी पूरी financial situation को समझना सबसे ज़रूरी कदम है।
👉 अपना Free Debt Assessment लें और जानें आपके लिए कौन-सा option सबसे सही रहेगा।
👉 Loan Settlement Options जानें और अपनी situation के हिसाब से सही फैसला लें।