If you’ve missed a few EMIs on your Kotak loan or credit card, the calls and reminders can start to feel heavy very quickly. Many borrowers then hear the word “settlement” and wonder if it can end the problem for good.
Here’s the honest answer. Kotak Mahindra Bank loan settlement means you pay the bank a one-time amount that is less than your total dues, and the bank closes the account. It can give real relief to someone in genuine financial trouble. But it is not automatic, it is not guaranteed, and it leaves a mark on your CIBIL report.
This guide walks you through the full Kotak loan settlement process in simple words: who may qualify, how to talk to the bank, which documents to keep ready, what your settlement letter must say, and what happens to your credit score afterwards.
What Is Kotak Mahindra Bank Loan Settlement?
A loan settlement is a compromise between you and the bank. You can’t repay the full outstanding amount, so the bank agrees to accept a smaller one-time payment (or a few short instalments) and treats the account as settled.
Think of it this way. Suppose you owe ₹4 lakh on a Kotak personal loan after interest and penalties have added up. If you lost your job and genuinely can’t pay that, you may ask the bank whether it will accept a lower amount to close the matter. If the bank agrees, it gives you the offer in writing, you pay as agreed, and the bank stops recovery on that account.
The catch is in the reporting. Because the bank received less than it was owed, your credit report usually shows the account as “Settled”, not “Closed”. Lenders read these two words very differently, which we explain later in this guide.
Does Kotak Mahindra Bank Offer Loan Settlement?
Yes, Kotak Mahindra Bank can consider a compromise settlement, like most Indian banks. The Reserve Bank of India’s 2023 framework on compromise settlements allows regulated lenders to settle dues, but only under their own board-approved policy.
That last part matters. Settlement is the bank’s commercial decision, not your legal right. The bank looks at how much it can realistically recover, your financial position and its internal rules. It may agree, offer different terms, or say no.
So be careful with anyone who promises a “guaranteed” settlement or a fixed waiver like “pay only 30%”. No one outside the bank can promise that.
Who May Be Eligible for Kotak Loan Settlement?
There is no fixed public checklist, but banks usually consider settlement when repayment has become genuinely difficult, not just inconvenient. Situations that commonly lead to a settlement request include:
- Job loss, layoff or a long gap in income
- A serious medical emergency in the family
- A business that has shut down or is running at a heavy loss
- A large, unavoidable expense that wiped out savings
- The death or disability of an earning family member
The bank will want to see that the hardship is real and that full repayment is unlikely in the near future. If you can still manage EMIs with some adjustment, the bank may suggest restructuring or a revised plan instead.
You may also hear that settlement starts only after 90 days of missed EMIs. That number relates to when banks classify a loan as a non-performing asset. It is not a universal settlement rule, so don’t rely on it. Ask the bank about your own account.
Which Kotak Loans and Credit Products Are Covered?
Settlement talks are most common for unsecured debt, where the bank has no asset to fall back on.
| Product | What to know |
|---|---|
| Personal loan | The most common case for settlement requests |
| Credit card | Often settled after dues grow due to interest and late fees |
| Business loan (unsecured) | Possible, usually with proof of business loss |
| Consumer durable loan | Smaller amounts; settlement may be considered |
| Home loan or loan against property | Secured by property, so the bank has other recovery options; the process and risks are very different |
| Car or two-wheeler loan | Secured by the vehicle; repossession is a real possibility |
Secured loans aren’t impossible to settle, but the bank holds collateral, so its approach is different. If your loan is secured, speak to the bank and a qualified advisor before you stop paying anything.
How to Settle a Kotak Mahindra Bank Loan: Step by Step
Take it one step at a time. Rushing usually leads to a worse deal or, worse, paying the wrong person.
- Know your exact dues. Ask Kotak for an updated loan or card statement. Note the principal, interest, penalties and other charges separately.
- Work out what you can really pay. List your income, essential expenses and any lump sum you can arrange from savings or family. Your offer should come from this number, not from a guess.
- Collect proof of hardship. Termination letter, medical bills, bank statements showing reduced income, business loss records. Real documents make your request believable.
- Contact the bank through official channels. Write to Kotak’s customer service or collections team using the contact details on the official Kotak website or your statements. Explain your situation briefly and honestly, and ask whether a settlement can be considered.
- Discuss the offer. The bank may propose an amount, or ask you to propose one. Expect some back and forth.
- Get the offer in writing before paying. Never pay a single rupee on a verbal promise. Wait for a settlement letter on Kotak’s letterhead.
- Pay only to the bank. Use the payment method mentioned in the letter, to an account in Kotak Mahindra Bank’s name. Keep every receipt.
- Collect the closure proof. After your final payment, ask for a written confirmation that the account is settled and no further dues are payable.
How to Negotiate a Kotak Loan Settlement
Negotiating with a bank feels intimidating, but it is mostly about being clear, honest and patient.
- Lead with facts, not emotion. Share what happened, when it happened and what you can pay now. Short and specific works better than long explanations.
- Start with a realistic offer. An offer that is far too low may be rejected outright. One you can’t actually arrange will collapse later.
- Ask what is included. Confirm whether the amount covers principal, interest, penalties and all other charges, so nothing pops up later.
- Request a short instalment plan if needed. If a lump sum is hard, ask whether the amount can be paid in two or three parts, and get the dates written in the letter.
- Keep a record of every conversation. Note the date, the person’s name and what was said. Follow important calls with an email.
- Know your rights with recovery agents. RBI rules require recovery agents to behave respectfully. They cannot threaten, abuse or harass you, or call at odd hours. If that happens, complain to the bank in writing.
If the bank doesn’t resolve your complaint within 30 days, or you’re unhappy with its reply, you can approach the RBI Ombudsman through the RBI’s online complaint portal.
Documents Required for Kotak Loan Settlement
Requirements vary by case, but keeping these ready will save time:
- Loan account number or credit card number, and the latest statement
- PAN card and Aadhaar or another valid ID
- Address proof
- Income proof, such as recent salary slips or ITRs, or proof that income has stopped
- Last six months of bank statements
- Hardship proof: termination or layoff letter, hospital bills, business loss records
- Copies of all emails, letters and notices exchanged with the bank
Make a single folder, physical or on your phone, and keep copies of everything you submit.
What Should a Kotak Loan Settlement Letter Include?
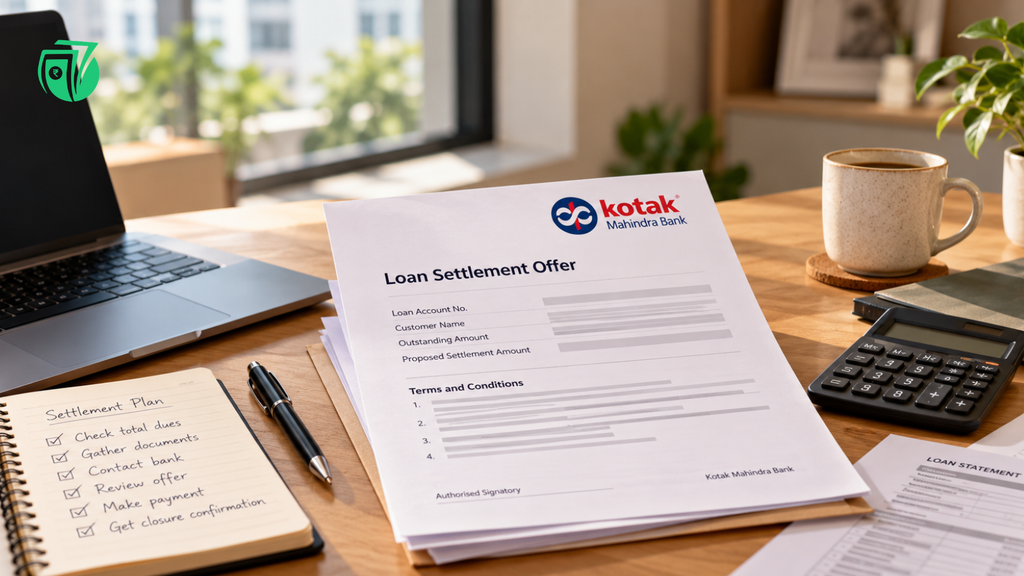
The settlement letter is your most important protection. Read every line before you pay. A proper Kotak loan settlement letter should show:
- Kotak Mahindra Bank’s official letterhead and an authorised signatory
- Your name and correct loan or card account number
- The total outstanding amount and the agreed settlement amount
- Payment deadline, and instalment dates if any
- Clear wording that the amount is a full and final settlement of this account
- Official payment details in the bank’s name
- A statement that no further dues will be claimed after payment
If anything is missing or unclear, ask the bank to correct it before paying. If someone asks you to transfer money to a personal account or UPI ID, stop. Call the bank on its official number and verify first.
After the final payment, ask for a No Dues Certificate or a closure letter. Keep it safely for years, because you may need it if the account ever shows wrong details on your credit report.
How Does Kotak Loan Settlement Affect Your CIBIL Score?
This is the part most people underestimate. Settlement ends your dues, but it does not erase your credit history.
When you repay a loan in full, the bank reports it as Closed. When you settle for less, it is usually reported as Settled. Future lenders see “Settled” as a sign that a past lender took a loss, so they may reject your application, ask for a higher interest rate or offer a smaller amount.
Your score may also already have dropped because of the missed EMIs before settlement. How much it falls, and how long it takes to recover, depends on your full credit profile. Nobody can honestly promise a fixed number.
Also note that under the RBI framework, a lender may apply a cooling period before giving fresh credit to a borrower whose account was settled.
Can you change “Settled” to “Closed” later? Some banks allow it if you pay the remaining waived amount. Ask Kotak whether this is possible for your account and get the updated closure letter in writing.
Loan Settlement vs Foreclosure vs Restructuring
Settlement is only one option. Compare it with the others before deciding.
| Option | What it means | Amount you pay | Credit report status | Best suited when |
|---|---|---|---|---|
| Full repayment | Pay all dues as per schedule | Full amount | Closed | You can manage EMIs, even with effort |
| Foreclosure | Pay the full balance early in one go | Full outstanding, plus any foreclosure charges | Closed | You have extra funds and want to save on interest |
| Restructuring | Bank changes EMI amount or tenure | Full amount, spread differently | Usually reported as restructured | Income has dropped temporarily but will recover |
| Settlement | Bank accepts less than total dues | Reduced, one-time amount | Settled | Hardship is serious and full repayment isn’t realistic |
If there’s a realistic chance you can repay fully, even slowly, restructuring is usually kinder to your credit future than settlement.
What to Do After Completing the Settlement
Paying the amount is not the finish line. A few follow-ups protect you from trouble later.
- Get your closure documents. Collect the No Dues Certificate or settlement closure letter and keep all payment receipts.
- Check your credit report after a few weeks. Banks report to credit bureaus on a regular cycle. Download your CIBIL report and confirm the account shows as settled with zero balance.
- Raise a dispute if anything is wrong. If the report still shows dues, raise a dispute with CIBIL and share your closure letter with Kotak.
- Start rebuilding slowly. Pay every remaining bill on time. If needed, a small secured credit card against a fixed deposit can help you build a fresh repayment record.
- Keep credit use low. Avoid applying for many loans or cards at once, and keep card usage well below your limit.
Credit rebuilding takes time, but steady, on-time payments do add up.
Frequently Asked Questions
Can I settle my Kotak Mahindra Bank personal loan?
A borrower facing genuine financial hardship can contact Kotak Mahindra Bank to ask whether a compromise settlement is available. Approval depends on the bank’s applicable policy and individual circumstances.
Does Kotak Mahindra Bank loan settlement affect CIBIL?
A loan settled for less than the full outstanding amount may be reported as Settled rather than Closed. This can negatively affect creditworthiness and future loan approvals.
What documents are required for Kotak loan settlement?
Depending on the case, borrowers may need their loan statement, identity documents, income records, evidence of financial hardship and previous written communication with the bank.
Is Kotak Mahindra Bank loan settlement guaranteed?
No. A compromise settlement is not a borrower’s automatic right. The bank considers requests under its applicable policy and commercial judgement.
Final Thoughts
Kotak Mahindra Bank loan settlement can be a genuine way out when your finances have truly broken down. But it works best when you treat it as a careful, documented process: know your dues, be honest about your situation, get every term in writing and pay only through official bank channels.
Before you choose settlement, also ask whether restructuring could work for you. And once it’s done, focus on rebuilding your credit one on-time payment at a time.
If you’re feeling stuck and want help understanding your options, the TrueSettle team can walk you through your situation and what to expect. Final approval and terms always rest with the bank.
Disclaimer: This article is for general information only and is not legal or financial advice. Settlement approval, terms and credit reporting depend on Kotak Mahindra Bank’s policies and your individual case. Please verify details with the bank or a qualified professional before making any decision.