You took the loan with every intention of repaying it. Then something changed — a job loss, a business that slowed down, a medical bill nobody saw coming. Now the EMIs are piling up, the calls from the branch have started, and you’re wondering if there’s any way out that doesn’t take years.
For many borrowers, there is. If you’re trying to figure out how to settle a Punjab National Bank loan, this guide walks you through it in plain language: what settlement actually means, who usually qualifies, how the process works, which documents you’ll need, and what it will do to your CIBIL score.
One thing upfront, because it matters: settlement is not automatic. PNB decides every case under its own Board-approved policy, and the terms depend on your account, your loan type and how long it has been overdue. Nobody — not an agent, not a consultant, not us — can promise you a fixed discount. What you can do is walk in prepared, ask the right questions and protect yourself at every step.
What Is Punjab National Bank Loan Settlement?
A loan settlement is an agreement where PNB accepts less than the full amount you owe and treats the loan as closed once you pay that agreed amount. Banks usually call this a One Time Settlement (OTS) or a compromise settlement.
Why would a bank agree to take less? Because chasing a bad loan for years — through notices, recovery agents, tribunals or court — costs the bank time and money too. If your situation is genuinely difficult, recovering a reasonable amount now can make more sense for the bank than waiting for a full recovery that may never come. In India, banks negotiate these deals within the RBI’s June 2023 Framework for Compromise Settlements and Technical Write-offs and their own Board-approved policies.
Here’s the part many borrowers miss: a settled loan is not the same as a fully repaid loan.
| Fully repaid (Closed) | Settled | |
|---|---|---|
| What you pay | The entire outstanding amount | A lower amount agreed with the bank |
| How it shows on your credit report | “Closed” | Usually “Settled” |
| Effect on future loans | Positive or neutral | Lenders may see it as a red flag for some time |
| Best for | Borrowers who can still pay in full | Borrowers in genuine, long-term hardship |
So settlement solves one problem — an unpayable debt — but leaves a mark you’ll need to work on later. Keep that trade-off in mind as you read on. [Internal link: loan settlement process in India]
Does Punjab National Bank Offer Loan Settlement?
Yes — PNB does settle loans, but in two different ways, and it helps to know which one you’re dealing with.
1. Time-bound Special OTS schemes. Every so often, PNB launches a scheme with fixed rules: who qualifies, what percentage you pay, and a deadline. For example, PNB’s Special OTS Scheme FY 2022-23 covered NPA accounts with dues up to ₹5 crore and ran from 1 July 2022 to 31 March 2023. That scheme has ended — we mention it only to show how these schemes are built.
2. Case-by-case compromise settlement. Outside of special schemes, PNB can still consider a settlement proposal under its Board-approved compromise policy. Here there’s no fixed chart; the bank looks at your account and your circumstances and decides.
Schemes open and close, and their rules change each time. So before you plan anything, ask your branch or the Circle SASTRA office (PNB’s recovery wing) which scheme or policy currently applies to your account. Don’t rely on a figure you read online, including on this page.
Who Is Eligible for PNB Loan Settlement?
There’s no single rule that fits everyone, but these are the factors PNB typically looks at:
- Your account status. Settlement is usually offered on accounts that have turned NPA — generally overdue for more than 90 days. If you’re only a month or two behind, the bank is more likely to push for regular repayment or restructuring.
- Genuine financial hardship. Job loss, salary cuts, business losses, serious illness or a death in the family — and, importantly, proof of it.
- Type of loan. Personal loans, credit cards, business/MSME loans, agriculture loans, education loans and secured loans like home or property loans can all be handled differently. Don’t assume the rule for a personal loan applies to your business loan.
- Security behind the loan. For secured loans, the market value of the property or asset matters a lot. Higher security usually means the bank expects a higher settlement.
- Your repayment history and conduct. Borrowers who stayed in touch with the bank and engaged honestly tend to have an easier time.
Some cases are usually excluded altogether. The FY 2022-23 scheme, for instance, did not cover fraud or wilful default cases, staff accounts, gold loans, accounts in NCLT, or accounts that already had a settlement in force. Exclusions in a current scheme may differ, so check.
How Much Can You Pay to Settle a PNB Loan?
The honest answer: it depends, and anyone quoting you a fixed “pay only 30%” figure without seeing your account is guessing. The amount PNB accepts usually depends on:
- How long the account has been NPA. Older bad loans tend to settle at lower percentages.
- Whether the loan is secured, and what the security is worth today.
- The outstanding balance and the type of loan.
- Your proof of hardship and what you can realistically pay.
- Extra charges. Legal costs, insurance and other expenses the bank has already spent may be recovered on top of the settlement amount.
To give you a feel for how these factors play out, here’s what the expired FY 2022-23 Special OTS scheme set for a few account types. These were percentages of the balance outstanding on the date the proposal was received:
| Account type under the FY 2022-23 scheme (expired) | OTS amount |
|---|---|
| Sub-standard NPA (most loans) | 85% |
| Sub-standard education loan up to ₹7.5 lakh | 70% |
| Doubtful-I, non-agri, balance up to ₹1 lakh | 50% |
| Doubtful-III or Loss, non-agri, balance up to ₹1 lakh | 25% |
Source: PNB Special OTS Scheme FY 2022-23. Treat this as an example of the logic, not a price list. The current terms for your account may be quite different.
How to Apply for PNB Loan Settlement
Here’s how the process usually unfolds, step by step:
- Confirm where you stand. Get your latest loan account statement and ask the branch for your current outstanding and NPA status. Ask which settlement scheme or policy applies to your account right now.
- Work out what you can actually pay. Look at your savings, any help from family, and assets you could sell. Make an offer you can genuinely honour — a failed settlement puts you back at square one.
- Write a settlement request. Address it to the Branch Manager (or the Circle SASTRA Head, if your account has moved there). Explain your hardship briefly and honestly, mention your loan account number, and state your proposed amount and payment timeline.
- Attach supporting documents. Proof of identity, loan details and proof of hardship (see the next section). Keep a stamped copy or acknowledgement for yourself.
- Pay any upfront amount, if the scheme requires one. Some schemes ask for a deposit with the proposal. Under the FY 2022-23 scheme, for example, it was at least 20% of the OTS amount for balances up to ₹25 lakh. Pay only into your loan account at the branch or through official PNB channels.
- Let the bank review it. The bank may verify your documents, value any security and come back with a counter-offer. Stay reachable and respond quickly.
- Get the sanction letter in writing. Do not pay the balance until you have an official PNB sanction letter showing the settlement amount, due dates and conditions.
- Pay exactly as agreed. Stick to the dates. In the FY 2022-23 scheme, missing even one instalment meant the whole OTS failed.
- Collect your closure papers. Ask for the settlement/No Dues certificate and, for secured loans, the return of original documents and release of the charge on your property.
Never hand cash to a recovery agent or pay into a personal account. PNB’s own recovery agency policy says agency staff must not accept cash — cash recoveries are to be deposited directly at the branch.
Documents Required for PNB Loan Settlement
The exact list depends on your loan and your branch, but keep these ready:
- Identity and address proof — Aadhaar, PAN and a current address proof.
- Loan details — loan account number, sanction letter (if you have it) and the latest account statement showing the outstanding amount.
- Proof of income — recent salary slips, bank statements or ITRs, whatever shows your current earnings.
- Proof of hardship — a termination or relieving letter, medical bills and reports, business loss statements, or a death certificate, depending on your situation.
- Your written settlement request — signed, dated, with a copy for your records.
- For secured loans — property papers and any recent valuation, if the bank asks.
A tidy, complete file makes your case easier to approve. A vague request with no proof often gets ignored.
How Does PNB Loan Settlement Affect Your CIBIL Score?
Let’s be straight about this: settlement usually hurts your credit profile. Once you settle, the account is typically reported to credit bureaus as “Settled” rather than “Closed.”
To future lenders, “Settled” says the bank had to accept less than it was owed. That can mean:
- Loan or credit card applications getting rejected for a while.
- Higher interest rates or smaller limits when you are approved.
- Extra questions from lenders about what happened.
That said, an account stuck in default with mounting dues and recovery action is often worse for your score — and your peace of mind. Settlement stops the bleeding; rebuilding is the next job.
How to rebuild after settlement:
- Check your CIBIL report 30–60 days after paying, and confirm the account is updated correctly.
- Raise a dispute with the bureau if the record is wrong — keep your settlement letter and receipts handy.
- Start small: a secured credit card against a fixed deposit, used lightly and paid in full every month.
- Pay every bill on time. Consistency over 12–24 months matters more than anything else.
If you later have the money, you can ask PNB whether paying the waived amount would let the account be updated from “Settled” to “Closed.” This is at the bank’s discretion, so get any such arrangement in writing. [Internal link: how loan settlement affects your CIBIL score]
PNB Loan Settlement vs Loan Restructuring
Before you settle, ask the bank about restructuring. It’s a different tool for a different problem.
| Loan settlement (OTS) | Loan restructuring | |
|---|---|---|
| What happens | You pay a reduced amount and the loan ends | Your repayment terms change — longer tenure, lower EMI, or a short break |
| Total you pay | Less than the full dues | Usually the full dues, sometimes more interest over time |
| Credit report | Usually marked “Settled” | Marked “Restructured,” generally seen as less damaging |
| Best when | Your hardship is long-term and full repayment isn’t realistic | Your problem is temporary and you expect income to recover |
If you think you’ll be back on your feet in six months to a year, restructuring may protect your credit better. If there’s no realistic path to repaying in full, settlement may be the more honest option. [Internal link: loan settlement vs loan restructuring]
Before You Settle Your PNB Loan: 5 Questions to Ask the Bank
Walk into the branch with these written down. The answers will tell you whether the deal is right for you.
- Is my loan account eligible under the settlement policy that applies today? Ask which scheme or policy it is, and when it ends.
- What is the total approved settlement amount, and exactly what does it cover? Principal, interest, penal charges, legal costs — make sure nothing is left hanging.
- What is the last date for payment, and what happens if I miss it? Some offers lapse completely after one missed instalment.
- How will the account be reported to the credit bureaus? Ask whether it will show as “Settled” and when the update will be sent.
- What written confirmation will I receive after I finish paying? You want a settlement or No Dues certificate, at the very least.
What to Check Before Accepting a PNB Settlement Offer
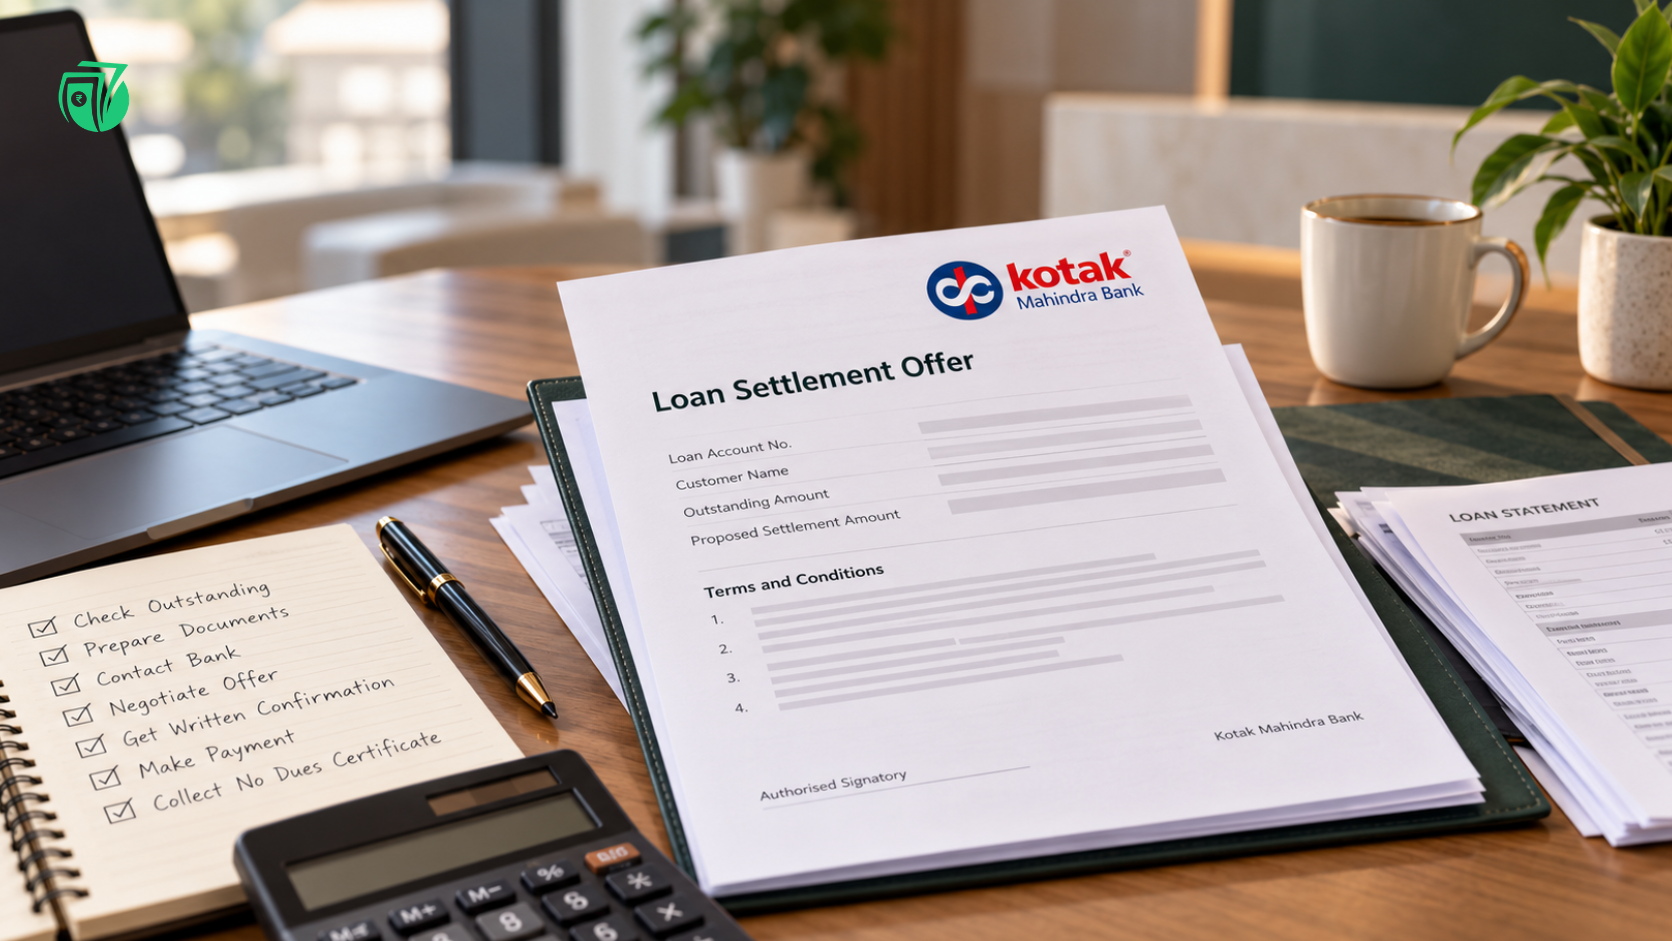
Once the offer arrives, read it slowly. Before you pay a single rupee beyond any required deposit, make sure:
- The offer is on official PNB letterhead, signed by an authorised officer.
- Your name, loan account number and the settlement amount are correct.
- Payment dates and the instalment schedule (if any) are clearly written.
- It says the amount is in full and final settlement of the account.
- It explains what happens if you pay late or miss an instalment.
- You’re paying only into your loan account, at the branch or through official PNB channels — never cash to an agent, never a personal UPI.
- You keep every receipt, transaction reference and letter in one folder.
- For secured loans, it states when original documents will be returned and the charge on your property released.
If anything is unclear, ask for it in writing before you pay. A genuine offer will survive a few questions; pressure to “pay today or lose the deal” is a warning sign.
Frequently Asked Questions
1. How can I settle my Punjab National Bank loan?
Start by confirming your outstanding amount and NPA status with your branch. Then submit a written settlement request to the Branch Manager or Circle SASTRA office, with proof of hardship and a realistic offer. If PNB approves, you’ll receive a sanction letter. Pay exactly as it says, through official channels, and collect your settlement or No Dues certificate at the end.
2. Does Punjab National Bank offer a One Time Settlement scheme?
Yes. PNB launches time-bound Special OTS schemes from time to time, and it can also consider settlements case by case under its Board-approved policy. Schemes have fixed start and end dates, so ask your branch which scheme, if any, is open right now and whether your account is covered.
3. Who is eligible for PNB loan settlement?
Usually, borrowers whose accounts have become NPA and who can show genuine financial hardship — job loss, business losses, illness and similar situations. The loan type, security and repayment history also matter. Fraud and wilful default cases are generally excluded. Final approval always rests with the bank.
4. How much loan amount can PNB waive under OTS?
There’s no fixed waiver that applies to everyone. The amount depends on how long the account has been NPA, the outstanding balance, the value of any security and the scheme in force. Older, unsecured bad loans tend to settle at lower percentages than recent or well-secured ones. Your sanction letter is the only reliable figure.
5. Can I settle my PNB personal loan if I have missed several EMIs?
Often, yes — in fact, settlement is mostly considered for accounts that are already well overdue and classified as NPA. Missing EMIs alone doesn’t guarantee approval, though. You’ll still need to show genuine hardship and make a reasonable, payable offer.
6. Does PNB loan settlement affect my CIBIL score?
Yes. A settled loan is usually reported as “Settled,” which lenders treat as negative. It can make new credit harder to get for a while. You can rebuild over time with on-time payments and careful use of a small, secured credit line.
7. What documents are required for PNB loan settlement?
Typically: Aadhaar, PAN and address proof; your loan account details and latest statement; income proof such as salary slips or bank statements; documents proving hardship; and a signed settlement request. For secured loans, property papers may be needed. Your branch may ask for more.
8. How long does the PNB loan settlement process take?
It varies by case, scheme and how quickly paperwork moves. Simple cases can be quicker; secured loans needing valuation usually take longer. Once approved, payment windows are often a few months — in the FY 2022-23 scheme, borrowers were asked to pay within 3 months of approval.
9. What is the difference between PNB loan settlement and loan closure?
Loan closure means you repaid everything, and your report shows “Closed.” Settlement means the bank accepted a reduced amount, and your report usually shows “Settled.” Both end the debt, but closure is far better for your credit history.
10. Can I apply for another loan after settling my PNB loan?
You can apply, but approval may be harder for some time, especially with banks. Build a clean repayment record first, check that your credit report reflects the settlement correctly, and consider asking PNB whether paying the waived amount could update the status to “Closed.”
Final Word
Settling a Punjab National Bank loan isn’t a shortcut, and it isn’t a scam either — when done properly, it’s a legitimate way out of a debt you genuinely can’t repay. Know your account status, confirm the current PNB policy, make an honest offer, and don’t pay a single rupee without a written sanction letter.
If you’d like help reading your loan statement or preparing your settlement request, talk to the TrueSettle team. We’ll tell you plainly whether settlement makes sense for you — and what to expect if it does.
Related reading: [Internal link: credit card settlement process] · [Internal link: how to settle an HDFC Bank loan] · [Internal link: how to settle an Axis Bank loan]
Disclaimer: This article is for general information only and is not legal or financial advice. Settlement terms are decided solely by Punjab National Bank under its applicable policies.