If you have a loan or credit card with Punjab National Bank and the EMIs have started to feel impossible, you are not alone. A job loss, a medical emergency or a business that slowed down can turn a manageable loan into a monthly worry. The calls start, the penalties pile up, and it feels like there is no way out.
There often is a way forward, though. One option many borrowers explore is a loan settlement. This guide explains, in plain language, how Punjab National Bank loan settlement works, who may be considered, what the process looks like and what it can mean for your CIBIL score. Read it fully before you make any decision.
What Is Punjab National Bank Loan Settlement?
Quick answer: Punjab National Bank loan settlement is an arrangement where the bank agrees to accept a reduced amount, usually as a lump sum or in a few instalments, to close a loan that the borrower cannot repay in full. It is often called a One Time Settlement (OTS) or compromise settlement, and it is approved only at the bank’s discretion.
In a normal repayment, you pay the full principal, interest and any charges until the loan is closed. In a settlement, the bank looks at your situation and may agree to close the account for less than the total outstanding. In some cases this can include relief on penal interest or charges, but nothing is automatic.
The key difference is how the account is reported afterwards. A fully repaid loan is reported as “Closed”. A settled loan is usually reported as “Settled”, which lenders read very differently. We cover that in the CIBIL section below.
Does Punjab National Bank Offer Loan Settlement?
Quick answer: Yes, Punjab National Bank does consider settlement and OTS proposals in suitable cases, and it has run OTS schemes for certain categories of loans in the past. However, settlement is not a right. Every proposal is decided under the bank’s current policy, by the right approval authority, based on your individual case.
This matters because many websites make it sound like settlement is a standard product you simply apply for. It isn’t. The bank will look at how much is outstanding, how long the account has been overdue, what security (if any) backs the loan, and whether you genuinely cannot repay in full. Two borrowers with similar loans can get very different answers.
Who May Be Eligible for PNB Loan Settlement?
Quick answer: PNB is more likely to consider a settlement when a borrower faces genuine, documented financial hardship, has fallen significantly behind on payments and can still arrange a realistic lump sum or short-term payment. There is no fixed checklist that guarantees approval.
The factors that usually matter are:
- Genuine hardship: Job loss, salary cut, serious illness, death of an earning family member or a business shutdown.
- Account status: Settlement is usually discussed for accounts that are seriously overdue. An account becoming an NPA does not automatically make you eligible.
- Repayment capacity: The bank wants to see that you can actually pay the amount you are offering.
- Proof: Termination letters, medical bills, bank statements or business records that support your story.
- Type of loan: Unsecured loans such as personal loans and credit cards are handled differently from secured loans like home or vehicle loans.
If you can still manage reduced EMIs, the bank may suggest restructuring instead of settlement. That is often better for your credit profile, so it is worth asking about first.
PNB Loan Settlement Process: Step by Step
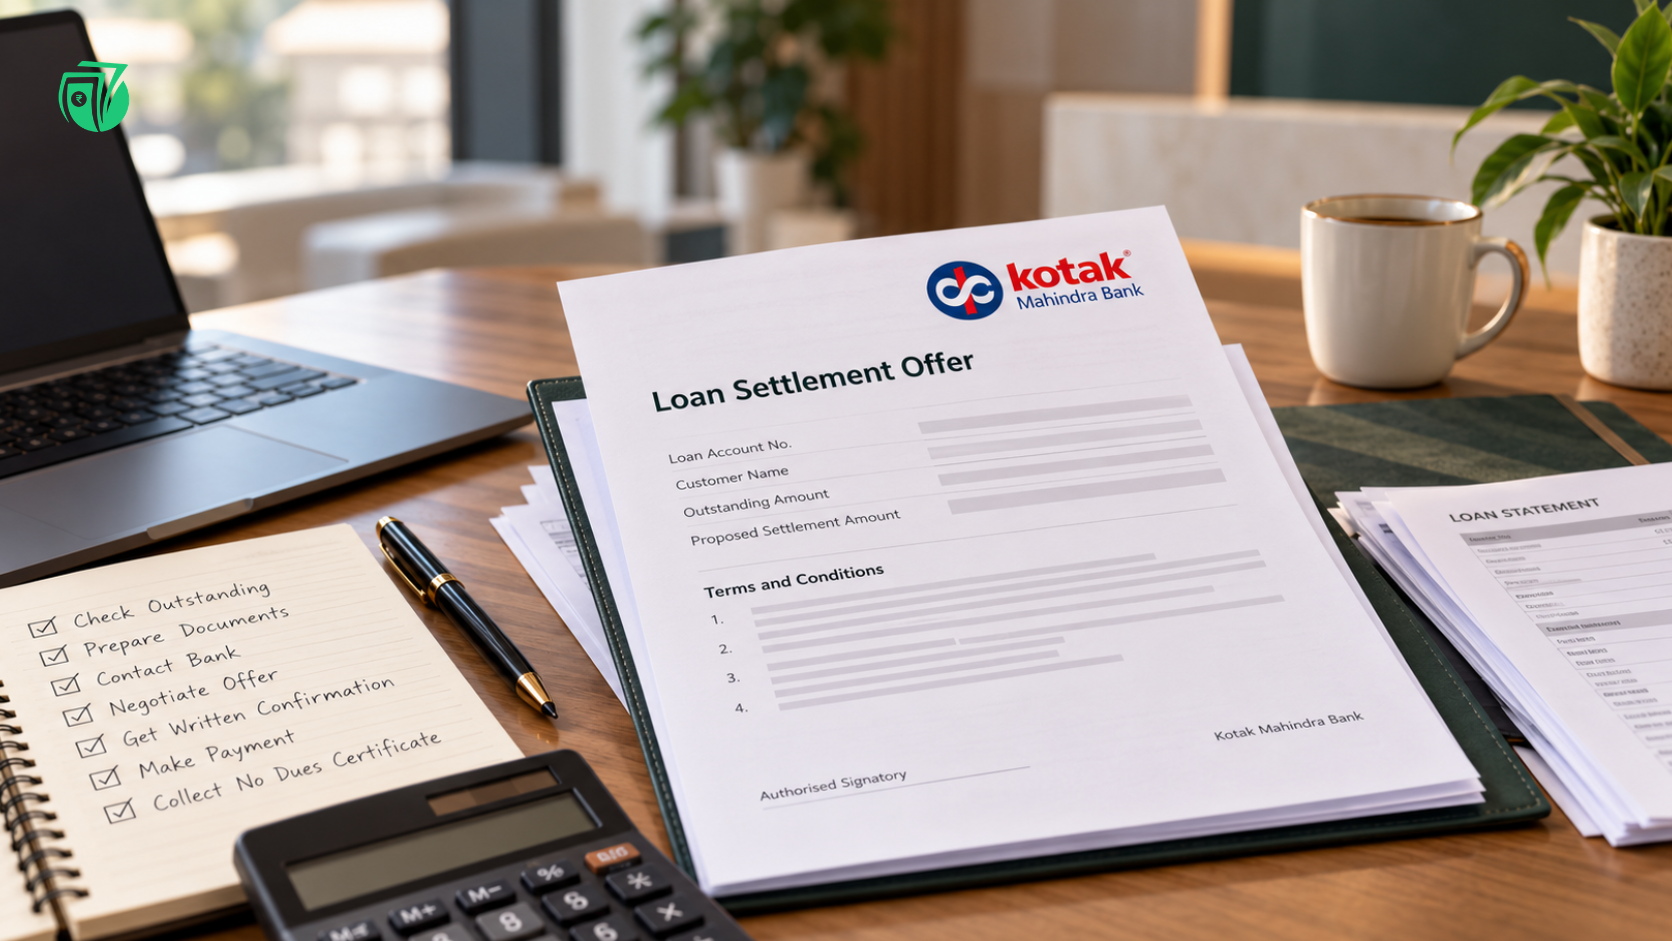
Quick answer: To settle a loan with Punjab National Bank, check your exact dues, collect proof of hardship, write to your home branch with a settlement proposal, negotiate, get the approved terms in writing, pay exactly as agreed and then collect your settlement letter and no-dues confirmation.
- Know your exact dues. Ask the branch for a statement showing principal, interest, penal charges and the total outstanding. You cannot negotiate well without this.
- Gather your documents. Keep proof of income loss, medical expenses or business losses ready, along with your KYC and loan papers.
- Approach your home branch in writing. Submit a simple letter explaining your situation and requesting a one time settlement. Keep a stamped copy or acknowledgement.
- Make a realistic offer. Propose an amount you can actually arrange. Offering more than you can pay and then defaulting again only makes things worse.
- Negotiate patiently. The bank may reject your first offer or come back with a counter-offer. This back-and-forth is normal.
- Get the approval in writing. Never pay a settlement amount based on a phone call or verbal promise. The sanction letter should state the amount, payment dates and that the account will be closed on full payment.
- Pay only to the bank. Use your loan account or an official bank channel and keep every receipt. Never pay cash to an agent or a personal account.
- Collect closure papers. After the final payment, ask for the settlement or closure letter and a no-dues confirmation.
Documents Required for PNB Loan Settlement
Quick answer: Most PNB settlement requests need your KYC documents, loan account details, recent bank statements, proof of financial hardship and a written settlement request. The branch may ask for more depending on your loan type.
- PAN card and Aadhaar or other KYC proof
- Loan account number, sanction letter or credit card statements
- Bank statements for the last 6 to 12 months
- Proof of hardship, such as a termination letter, salary slips showing a cut, medical bills or business loss records
- Your written settlement request or proposal letter
- Copies of any notices you have received from the bank
Keep photocopies of everything you submit, and note the date and the name of the officer you handed them to.
PNB Personal Loan vs Credit Card Settlement
Quick answer: Both PNB personal loans and PNB credit cards are unsecured, so the bank cannot recover dues by selling a pledged asset. That is why settlement is more commonly discussed for them. The main differences lie in how the dues build up and who handles the case.
| Personal loan | Credit card | |
|---|---|---|
| How dues build up | Missed EMIs plus overdue interest and charges | Revolving balance, high interest, late fees and over-limit charges |
| Who you usually deal with | Your home branch | The card division or its collection team |
| What to check before paying | That the sanction letter covers the full loan account | That the card account will be closed and no future charges added |
For credit cards, interest and fees can grow quickly once payments stop. So the outstanding figure you see after a few months may be much higher than what you actually spent. Ask for a clear break-up before you negotiate.
How Much Can You Save Through PNB OTS?
Quick answer: There is no fixed percentage or guaranteed discount in a PNB settlement. The amount the bank accepts depends on your outstanding dues, how long the account has been overdue, your hardship, any security and the bank’s own policy. Be cautious of anyone who promises a specific discount before reviewing your case.
You may come across claims online like “settle for half” or “save up to 50%”. These are marketing lines, not bank rules. Some borrowers get meaningful relief on interest and charges. Others are asked to pay most of the principal. Your outcome depends on your facts.
A useful way to think about it: the bank compares what it expects to recover through settlement against the time and cost of recovering it any other way. A clear, honest proposal backed by documents gives you the best chance of a fair offer.
Impact of PNB Loan Settlement on CIBIL Score
Quick answer: A PNB loan settlement usually hurts your CIBIL score because the account is reported as “Settled” instead of “Closed”. This tells future lenders that the bank accepted less than the full amount. It can make new loans or credit cards harder to get or more expensive for some time.
Here is what borrowers should keep in mind:
- The missed payments come first. Your score usually drops when EMIs are missed, well before any settlement happens.
- “Settled” is a negative remark. Many lenders treat it as a red flag when reviewing new applications.
- Recovery is possible. Paying all your other loans and cards on time, keeping credit use low and avoiding new defaults can help rebuild your score over time.
- You may be able to upgrade the status later. Some borrowers later pay the remaining waived amount and ask the bank to update the account to “Closed”. Ask the bank whether this is possible in your case.
Check your credit report a few weeks after settlement to confirm the account is updated correctly. If something is wrong, raise a dispute with the credit bureau and inform the bank.
PNB Loan Settlement Letter, NOC and No-Dues Confirmation
Quick answer: After paying the agreed settlement amount, you should get written confirmation from PNB that the account is settled and nothing more is payable. Keep this letter safely, because it is your proof if any dues are demanded later.
Before you pay, read the sanction letter carefully. It should clearly mention:
- Your name and loan or card account number
- The exact settlement amount and payment deadlines
- That the account will be treated as settled or closed on full payment
- That no further dues will be claimed on this account
After the final payment, ask for the settlement or closure letter and a no-dues certificate. For a secured loan, also confirm the release of any security, such as returning property papers or removing the bank’s charge on a vehicle.
Borrower Rights and Recovery Agent Guidelines
Quick answer: Even if you have missed EMIs, you have rights. Under Reserve Bank of India guidelines, banks and their recovery agents cannot threaten, harass or humiliate you or your family, and recovery calls are not allowed before 8 a.m. or after 7 p.m.
RBI’s 2022 directions on recovery agents make it clear that lenders are responsible for how their agents behave. In simple terms:
- Agents cannot use abusive language, threats or intimidation, verbally or physically.
- They should not contact your relatives, friends or colleagues to shame you.
- They should carry proper authorisation from the bank and identify themselves.
- Calls and visits should happen only within the permitted hours.
If you face harassment, write to your PNB branch and the bank’s grievance cell first. If the issue is not resolved, you can escalate to the RBI Ombudsman under the Integrated Ombudsman Scheme. You can also read PNB’s Fair Practices Code for Borrowers on the bank’s website and the relevant guidance on the RBI website.
PNB Loan Settlement vs Loan Restructuring
Settlement is not always the best choice. Before you decide, compare it with the other options.
| Regular repayment | Restructuring | Settlement | |
|---|---|---|---|
| What happens | You pay the full dues as scheduled | Loan terms change, such as a longer tenure or smaller EMIs | Bank accepts a reduced amount to close the loan |
| Total amount paid | Full | Full, sometimes more due to longer tenure | Less than the outstanding |
| Credit report | Best outcome | May carry a restructured remark | Usually shows “Settled” |
| Best suited for | Temporary cash crunch | Lower but steady income | Serious, long-term inability to pay |
If you can manage smaller EMIs, restructuring may protect your credit profile better. Settlement makes more sense when full repayment is genuinely out of reach.
How TrueSettle Can Help
Dealing with a bank when you are already under stress is hard. TrueSettle works with borrowers to understand their situation, review their dues and documents, and prepare a clear, honest settlement proposal. We also help you understand your rights if you are facing aggressive recovery calls.
We do not promise fixed discounts or guaranteed approvals, because the final decision always rests with the bank. What we offer is guidance, preparation and support at every step, so you can approach Punjab National Bank with confidence.
PNB Loan Settlement FAQs
Does Punjab National Bank offer loan settlement? Yes, PNB considers settlement or OTS proposals in suitable cases. Approval depends on the bank’s policy at the time and your individual circumstances, so it is never guaranteed.
How can I apply for PNB loan settlement? Write to your home branch explaining your financial difficulty and requesting a one time settlement. Attach proof of hardship and keep an acknowledged copy of your letter.
Can PNB settle a personal loan? Yes, personal loans are among the loans most commonly discussed for settlement because they are unsecured. The bank will still review your hardship, overdue period and repayment capacity.
Does PNB loan settlement affect my CIBIL score? Yes. A settled account is usually reported as “Settled”, which lowers your score and can make future credit harder to get. Timely repayment of other credit can help you rebuild over time.
What documents are needed for PNB loan settlement? Usually KYC documents, loan account details, recent bank statements, proof of hardship and a written settlement request. The branch may ask for more based on your loan.
What should I check before paying an OTS amount? Make sure you have a written sanction letter from PNB stating the amount, the deadlines and that the account will be closed on payment. Pay only through official bank channels and keep every receipt.
Final Thoughts
A Punjab National Bank loan settlement can give real relief when full repayment is no longer possible. But it is a serious decision with lasting effects on your credit. Understand your dues, compare settlement with restructuring, insist on everything in writing and know your rights as a borrower.
If you are unsure where to start, speak with the TrueSettle team. We will help you understand your options honestly, without false promises.
Disclaimer: This article is for general information only and is not legal or financial advice. Settlement terms and approvals depend on Punjab National Bank’s policies and your individual case.