If you’re negotiating a settlement on your IDFC FIRST Bank credit card, the settlement letter is the document that actually protects you. It’s the written record of what’s been agreed — and the reason you should never make a settlement payment based on a phone call alone.
This guide covers an illustrative sample settlement letter, the essential details to check for, how to verify a communication is genuine, and what to do once you’ve paid — including how settlement may affect your credit profile.
What Is an IDFC FIRST Bank Credit Card Settlement Letter?
A settlement letter is written documentation of the settlement terms agreed between you, the cardholder, and IDFC FIRST Bank. It generally specifies:
- The amount you’re required to pay
- The applicable conditions attached to that agreement
It provides a record of the arrangement that you can retain for future reference. You should verify this document through appropriate official channels before making any payment.
Important Distinction
| Document | Purpose |
|---|---|
| Settlement Letter | Documents the agreed settlement terms |
| Credit Card Statement | Shows transactions and outstanding dues |
| Post-Settlement/No-Dues Documentation | Confirmation after applicable settlement conditions are fulfilled |
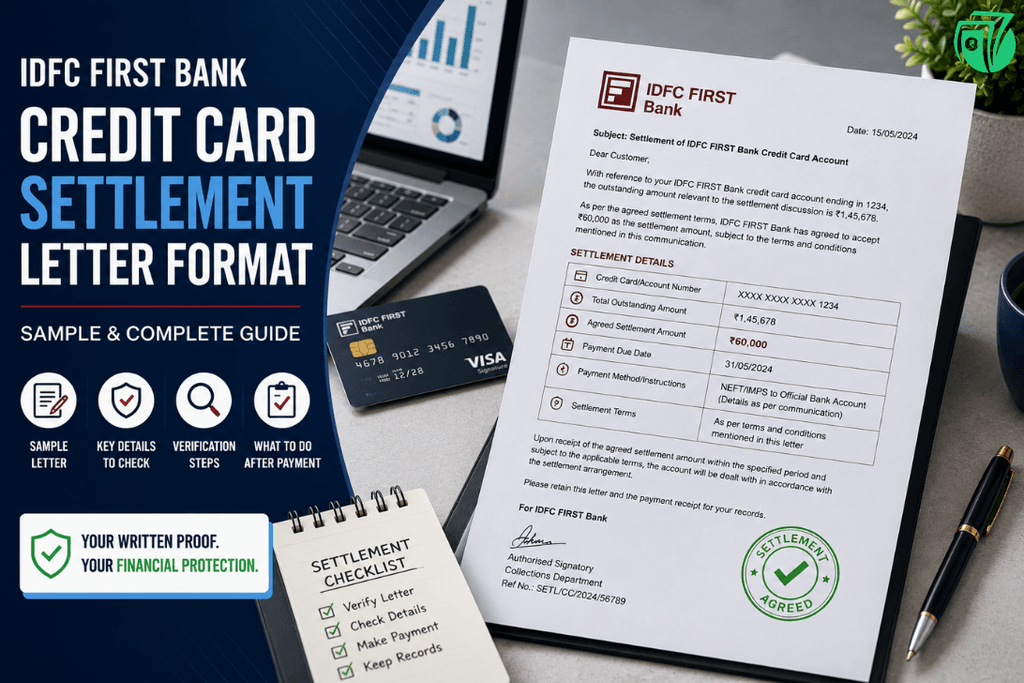
IDFC FIRST Bank Credit Card Settlement Letter Format – Sample
This is an illustrative reference only, not an official IDFC FIRST Bank document.
IDFC FIRST Bank Credit Card Settlement Letter – Illustrative Format
Date: [DD/MM/YYYY]
To,
[Cardholder’s Full Name]
[Address]
Subject: Settlement of IDFC FIRST Bank Credit Card Account
Dear [Customer Name],
With reference to your IDFC FIRST Bank credit card account ending in XXXX, the outstanding amount relevant to the settlement discussion is ₹[Total Outstanding].
As per the agreed settlement terms, IDFC FIRST Bank has agreed to accept ₹[Settlement Amount] as the settlement amount, subject to the terms and conditions mentioned in this communication.
Settlement Details:
- Credit Card/Account Number: XXXX XXXX XXXX [Last 4 Digits]
- Total Outstanding Amount: ₹[Amount]
- Agreed Settlement Amount: ₹[Amount]
- Payment Due Date: [Date]
- Payment Method/Instructions: [Official Payment Details]
- Settlement Terms: [Applicable Terms]
Upon receipt of the agreed settlement amount within the specified period and subject to the applicable terms, the account will be dealt with in accordance with the settlement arrangement.
Please retain this letter and the payment receipt for your records.
For IDFC FIRST Bank
[Authorised Signatory]
[Department]
[Reference Number, if applicable]
Disclaimer: This is a hypothetical sample created for educational purposes. It is not an official IDFC FIRST Bank settlement letter and should not be used as a substitute for a document issued by IDFC FIRST Bank or its authorised representative.
What Information Should an IDFC FIRST Credit Card Settlement Letter Contain?
1. Cardholder’s Full Name
Check that the name corresponds exactly with the bank’s records.
2. Credit Card or Account Details
The relevant account should be identifiable using appropriate masked details.
3. Total Outstanding Amount
The letter should clearly identify the outstanding amount relevant to the settlement.
4. Agreed Settlement Amount
The exact amount you’re expected to pay should be clearly stated.
5. Payment Deadline
Check the exact date by which the payment must be completed.
6. Payment Instructions
Verify the authorised payment method and destination carefully before transferring any money.
7. Settlement Terms and Conditions
Read every applicable term carefully.
8. Treatment of Remaining Dues
Understand how any remaining balance will be treated under the settlement arrangement.
9. Account/Credit-Reporting Status
Understand how your account is expected to be reported after settlement, subject to applicable reporting requirements.
10. Authorised Details
The communication should be verifiable as genuinely originating from IDFC FIRST Bank or an authorised channel.
Why Is an IDFC FIRST Credit Card Settlement Letter Important?
- Provides written evidence of the settlement arrangement.
- Helps prevent misunderstandings about the agreed settlement amount.
- Establishes the payment deadline and applicable conditions clearly.
- Allows you to review the terms before making payment.
- Can be retained with your payment records for future reference.
Key warning: do not rely solely on verbal assurances about settlement. Obtain and verify the applicable terms in writing before making any payment.
How to Get an IDFC FIRST Bank Credit Card Settlement Letter
Step 1: Review Your Outstanding Dues
Check your latest IDFC FIRST credit card statement and account information.
Step 2: Contact IDFC FIRST Bank Through Official Channels
Discuss your financial situation and ask about the options genuinely available for resolving your outstanding dues.
Step 3: Explain Your Financial Hardship
If requested, provide relevant supporting documentation.
Step 4: Discuss the Settlement Terms
Clarify:
- The proposed settlement amount
- The payment deadline
- The payment method
- Any applicable conditions
Step 5: Request Written Confirmation
Obtain the settlement terms in writing before making the agreed payment.
Step 6: Verify the Document
If anything appears unclear, confirm the settlement communication through official IDFC FIRST Bank channels.
How to Verify an IDFC FIRST Credit Card Settlement Letter
Verification Checklist
- Check your name.
- Check the relevant card/account details.
- Confirm the outstanding amount.
- Confirm the settlement amount.
- Check the payment deadline.
- Verify the payment instructions.
- Review all settlement conditions.
- Check the source of the communication.
- Contact IDFC FIRST Bank through official channels if you have doubts.
Red Flags to Watch For
- Requests to transfer money to an unrelated personal account.
- Pressure to make an immediate payment.
- Missing or inconsistent account information.
- Unclear treatment of the remaining dues.
- Suspicious or altered documents.
- Requests for sensitive information through unofficial channels.
What to Check Before Paying the Settlement Amount
☐ Correct name and account details
☐ Correct outstanding amount
☐ Exact settlement amount
☐ Payment deadline
☐ Official payment instructions
☐ Settlement terms and conditions
☐ Treatment of remaining dues
☐ Applicable credit-reporting information
☐ Document/source verification
Do not make payment until you understand and verify the applicable settlement terms.
What Happens After You Pay the IDFC FIRST Credit Card Settlement Amount?
Keep Your Payment Proof
Save:
- Your payment receipt
- A bank statement showing the transaction
- The settlement letter
- Relevant emails or messages
Obtain Appropriate Post-Settlement Documentation
Request relevant confirmation or documentation regarding your account after fulfilling the applicable settlement conditions.
Check Your Credit Report
After the applicable reporting period, review your credit report to ensure the account information has been updated accurately.
IDFC FIRST Credit Card Settlement vs Credit Card Closure
| Factor | Full Payment/Closure | Settlement |
|---|---|---|
| Amount paid | Full dues | Reduced amount agreed with lender |
| Remaining dues | None after full repayment | Handled according to settlement terms |
| Credit reporting | Generally more favourable | May be reported as “Settled” |
| Credit impact | Generally better | Can negatively affect future borrowing |
| Suitable for | Borrowers able to repay | Certain financial-hardship situations |
Key point: “Settled” and “Closed” are different credit-reporting statuses.
Does IDFC FIRST Credit Card Settlement Affect CIBIL?
- The settlement letter itself does not determine a CIBIL score.
- Settlement can affect your credit profile.
- The account may be reported as “Settled” instead of “Closed,” subject to applicable reporting requirements.
- Future lenders may consider this information when evaluating new credit applications.
- Consistent, responsible repayment behaviour afterward can help rebuild your creditworthiness over time.
There’s no fixed number of CIBIL points that applies to every borrower — the actual impact varies depending on individual credit history.
Can You Negotiate the Amount in an IDFC FIRST Credit Card Settlement?
- Settlement terms may be discussed with the lender where the option is available.
- Assess your actual repayment capacity honestly before making an offer.
- Keep genuine financial-hardship documentation available if requested.
- Don’t agree to an amount you cannot realistically pay within the specified timeline.
- Once terms are actually agreed, obtain them in writing.
What If the IDFC FIRST Settlement Letter Contains an Error?
Common Errors
- Incorrect name
- Wrong card/account details
- Incorrect outstanding balance
- Incorrect settlement amount
- Wrong payment deadline
- Unclear terms or conditions
What Should You Do?
Do not make payment based on an incorrect or unclear document. Contact IDFC FIRST Bank through official channels and request clarification or a corrected communication.
What If You Lose Your IDFC FIRST Credit Card Settlement Letter?
- Keep digital and physical copies whenever possible, from the outset.
- Check your registered email and SMS records.
- Contact IDFC FIRST Bank through official channels.
- Request appropriate confirmation or a copy of the settlement communication where available.
- Keep your payment records even if the original letter is lost.
Common Mistakes to Avoid
1. Paying Before Receiving Written Settlement Terms
Always wait for documentation first.
2. Treating an Online Sample as an Official IDFC FIRST Bank Document
The sample above is educational only.
3. Not Checking the Settlement Amount
Verify every figure carefully.
4. Ignoring the Payment Deadline
This can jeopardize the entire arrangement.
5. Paying Through an Unverified Channel
Confirm the authorised payment method first.
6. Not Keeping Payment Proof
Retain everything, ideally indefinitely.
7. Assuming “Settled” Means “Closed”
These are genuinely different statuses on your credit report.
8. Ignoring the Credit-Report Impact
Understand this before you commit.
Frequently Asked Questions
What is an IDFC FIRST Bank credit card settlement letter?
A written document confirming the agreed settlement amount and terms for resolving your IDFC FIRST Bank credit card dues.
How can I get an IDFC FIRST credit card settlement letter?
Contact IDFC FIRST Bank through official channels, explain your financial hardship, discuss the settlement terms, and request written confirmation before making any payment.
What should an IDFC FIRST credit card settlement letter contain?
Your name, card/account details, total outstanding amount, agreed settlement amount, payment deadline, payment instructions, settlement terms, and credit-reporting status.
Can I use an online IDFC FIRST settlement letter sample?
Only as an educational reference to understand what such a document should contain — never as an official document. The actual letter must come from IDFC FIRST Bank or its authorised channel.
Is an IDFC FIRST credit card settlement letter important?
Yes, it serves as written evidence of the agreed terms, which matters if any dispute arises later about what was actually agreed.
Should I pay before receiving the settlement letter?
No. Always wait for the official written settlement letter before making any payment.
How can I verify an IDFC FIRST credit card settlement letter?
Check your name and account details, confirm the settlement amount and deadline, review the payment instructions, and contact IDFC FIRST Bank’s official channels if anything seems unclear.
What happens after paying the IDFC FIRST credit card settlement amount?
You should receive confirmation of the payment and, where applicable, documentation confirming your account’s resolved status. Your credit report should be updated accordingly.
Does IDFC FIRST credit card settlement affect CIBIL?
Yes. A settled account is generally reported differently from a fully repaid one, typically as “Settled,” which can negatively affect your credit score and future borrowing.
What is the difference between a settlement letter and a post-settlement/no-dues document?
A settlement letter records the agreed terms before or at the time of payment. A post-settlement or no-dues document confirms afterward that the agreed dues have been resolved.
Final Takeaway
An IDFC FIRST Bank credit card settlement letter documents the agreed settlement terms between you and the bank. Check the settlement amount, payment deadline, payment instructions, and applicable conditions carefully before paying. Online samples should be used only as educational references — the actual settlement communication should always come from IDFC FIRST Bank or an authorised channel. Keep the settlement letter and your payment proof safely, and understand the potential impact of settlement on your credit profile.
Struggling with your IDFC FIRST Bank credit card dues? Get a personalised assessment of your debt situation and understand whether settlement or another repayment option may be suitable for you.
👉 Get a free debt assessment with TrueSettle
👉 Explore your settlement options before approaching IDFC FIRST Bank.