If you’ve taken a personal loan through the Navi app and you’re genuinely struggling to keep up with repayments, loan settlement is one option worth understanding properly — what it actually involves, what it costs, and what it means for your credit profile afterward.
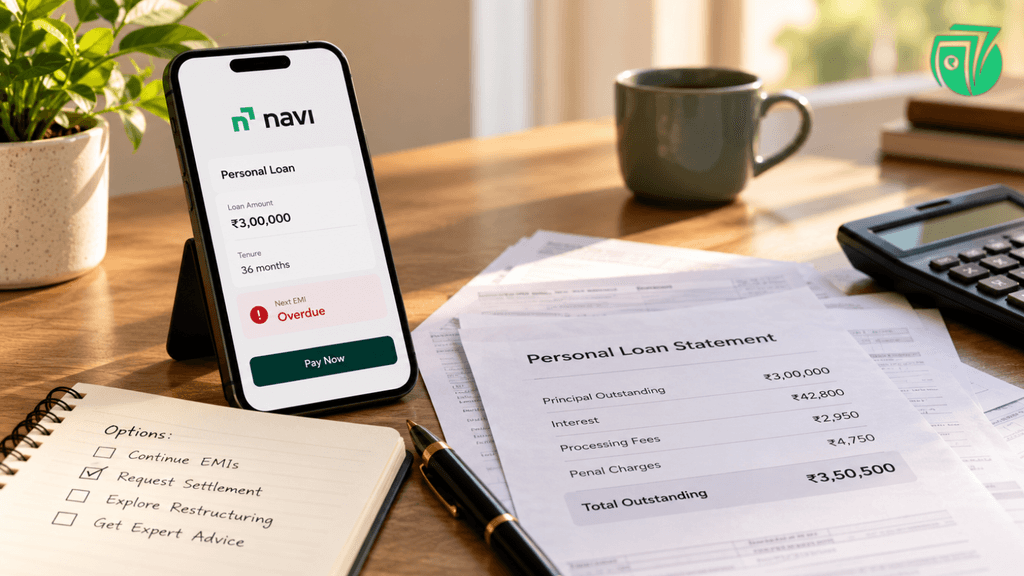
What Does It Mean to “Settle” a Navi Loan?
Settlement is an arrangement where Navi agrees to accept less than your full outstanding balance as a final resolution of your loan — commonly called a One-Time Settlement (OTS). It’s different from simply repaying the loan in full according to the original schedule.
A few things worth understanding upfront:
- Settlement requires Navi’s agreement. You can’t declare a settlement unilaterally — it has to be negotiated and accepted.
- It isn’t automatic debt forgiveness. Navi evaluates your account and circumstances before deciding whether to offer settlement, and on what terms.
- There’s no fixed, published settlement percentage. Any number you’ve seen quoted elsewhere (40%, 50%, etc.) is illustrative, not a rate Navi has publicly committed to for every borrower.
Who Might Navi Consider for Loan Settlement?
Settlement discussions are generally more relevant when:
- You’re facing genuine, documented financial hardship (job loss, income reduction, medical emergency, business loss)
- Your loan has been overdue for a meaningful period, not just a single missed EMI
- You have a realistic lump sum you can offer, even if it’s less than the full outstanding amount
- Continuing the original repayment schedule genuinely isn’t achievable
If you can still manage your EMIs, even with some difficulty, it’s worth exploring whether Navi offers restructuring or a revised repayment plan before pursuing settlement — settlement carries real credit-report consequences that are worth avoiding if full repayment remains realistic.
What Factors Affect a Navi Loan Settlement Amount?
- Your total outstanding balance — principal, interest, and any charges accrued.
- How long the loan has been in default, and its current status within Navi’s recovery process.
- Your documented financial hardship — specific, evidenced circumstances tend to carry more weight than a general statement of difficulty.
- Your realistic lump-sum capacity — what you can actually arrange to pay, not an aspirational figure.
- Your repayment history on the loan up to that point.
How to Approach Navi About Settling Your Loan
Step 1: Check Your Exact Outstanding Amount
Log into the Navi app or check your loan statement for the precise figure — principal, interest, and any penalty charges.
Step 2: Assess What You Can Realistically Offer
Work out your monthly income, essential expenses, other obligations, and any savings or lump sum you could genuinely put toward a settlement.
Step 3: Contact Navi Through Official Channels
Reach out via the Navi app’s support/help section, official customer care number, or email — avoid relying on informal messages from numbers you can’t verify as genuinely representing Navi.
Step 4: Explain Your Financial Hardship
Be specific and, where possible, provide supporting documentation (termination letter, medical bills, proof of reduced income).
Step 5: Discuss and Negotiate the Settlement Terms
Understand the proposed amount, payment deadline, and any conditions before agreeing to anything.
Step 6: Get the Settlement Terms in Writing
Never proceed based on a verbal assurance alone. Insist on written confirmation — ideally within the app, by email, or via an official letter — before making any payment.
Step 7: Make the Payment Through an Authorised Channel
Pay exactly the agreed amount, before the stated deadline, using Navi’s official payment method (through the app or another verified channel).
Step 8: Collect Post-Settlement Documentation
Keep your payment confirmation and request a closure or No Dues Certificate confirming the loan has been resolved.
What Should Written Settlement Confirmation Include?
Before paying, check that whatever Navi sends you (app confirmation, email, or letter) clearly states:
- Your name and loan account/reference number
- The total outstanding amount
- The agreed settlement amount
- The payment deadline
- The accepted payment method
- Confirmation of what happens to any remaining balance
- The status that will be reported to credit bureaus
Does Settling a Navi Loan Affect Your CIBIL Score?
Yes. A few points worth understanding:
- A settled loan is typically reported as “Settled,” not “Closed.” These are distinct statuses, and future lenders read them differently.
- This generally has a negative impact on your credit score and can affect your ability to borrow in the future for a period of time.
- The exact impact varies depending on your overall credit profile and history — there’s no fixed number of points every borrower loses.
- Responsible financial behaviour afterward — paying other obligations on time, keeping utilisation low — helps rebuild your credit profile gradually.
Navi Loan Settlement vs Full Repayment
| Factor | Full Repayment | Settlement |
|---|---|---|
| Amount paid | Full outstanding dues | Reduced, negotiated amount |
| Credit reporting | Generally reported as “Closed” | May be reported as “Settled” |
| Credit impact | Generally more favourable | Can negatively affect future borrowing |
| Best suited for | Borrowers who can repay in full | Genuine, documented financial hardship |
Common Mistakes to Avoid
- Assuming there’s a fixed settlement percentage Navi applies to every borrower — there isn’t one.
- Paying before getting written confirmation of the settlement terms.
- Making payments through an unverified channel instead of Navi’s official app or payment method.
- Stopping EMI payments just to force a settlement conversation — this damages your credit history without guaranteeing anything.
- Not keeping records of payment confirmations and settlement correspondence.
- Assuming “Settled” will show as “Closed” on your credit report — it typically won’t.
Frequently Asked Questions
Can I settle my Navi personal loan?
In many cases, yes, particularly if you’re facing genuine financial hardship and can offer a realistic lump sum. Navi evaluates each case individually.
What percentage will Navi accept for settlement?
There’s no fixed, published percentage. The amount depends on your outstanding balance, documented hardship, and Navi’s own assessment of your account.
How do I contact Navi about loan settlement?
Through the Navi app’s official support section, customer care number, or verified email — avoid relying on unverified calls or messages claiming to represent Navi.
Does Navi loan settlement affect my CIBIL score?
Yes. A settled loan is generally reported as “Settled” rather than “Closed,” which typically has a negative impact on your credit score for a period of time.
What documents do I need to request a settlement?
Typically your loan statement, income proof, and documentation supporting your financial hardship, such as a termination letter or medical bills.
Should I pay before receiving written settlement terms?
No. Always get the settlement amount, deadline, and terms confirmed in writing — through the app or official correspondence — before making any payment.
If you’re unsure whether settlement, restructuring, or another option fits your Navi loan situation, it helps to get a clear, honest assessment before deciding.
👉 Get a free debt assessment with TrueSettle
👉 Explore your debt resolution options before approaching Navi.