If you want to negotiate lower loan interest rate, the best time to speak with your lender is before you miss an EMI. Most borrowers only start thinking about negotiating after they’ve already missed a payment. By then, the conversation is about damage control — recovery calls, penalty charges, a credit score that’s already taken a hit. But there’s a much better time to have that conversation: before any of that happens, while you’re still current and your repayment record is clean.
This guide is about that earlier window — how to approach your lender for a lower interest rate while you’re still in a position of strength, rather than waiting until you’re not.
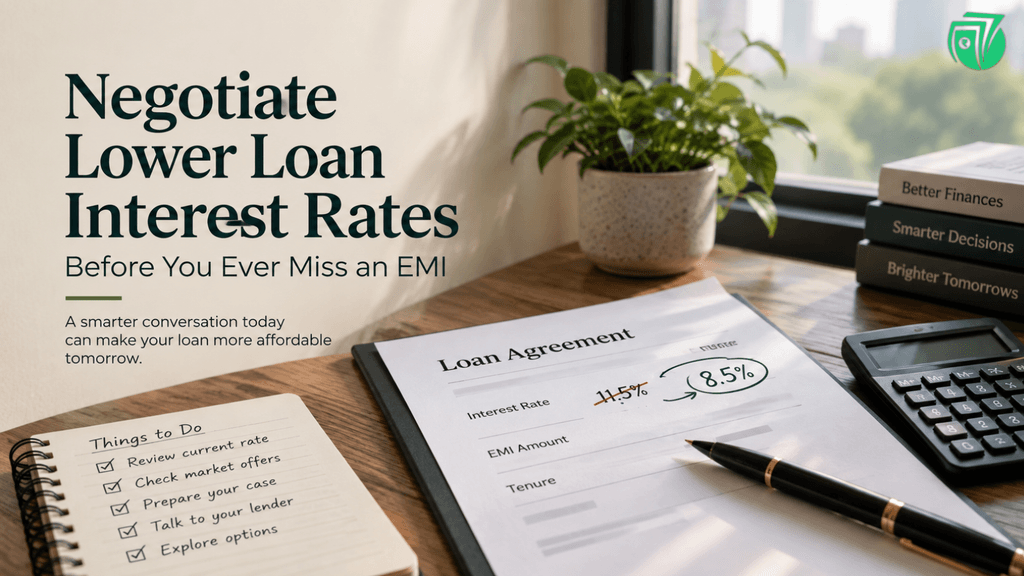
Why You Should Negotiate Before Missing an EMI
There’s a real, practical advantage to acting early:
- A borrower with a good repayment history typically has more room to negotiate. Lenders are more responsive to requests from accounts that have been reliably serviced.
- A lower interest rate reduces your overall repayment burden, sometimes meaningfully, without requiring you to change anything about your actual financial situation.
- Acting early is generally better than waiting until an account becomes overdue. Once you’re in default, the conversation shifts from “can my rate be reduced” to “how do we resolve this account.”
- Lenders generally prefer hearing from you before a crisis point, not after. A borrower who reaches out proactively is a very different conversation than a borrower already several EMIs behind.
The core idea here is simple: your leverage is highest when you don’t yet need anything urgently. Use that timing to your advantage.
Can You Negotiate Lower Loan Interest Rate?
In many cases, yes — but it’s not guaranteed, and it depends on a combination of factors:
- Lender policies — some lenders have formal rate-review processes; others don’t.
- Loan type — home loans, personal loans, and other loan categories often have different flexibility around repricing.
- Your credit history — a stronger credit profile generally supports a stronger case.
- Your existing repayment record — consistency matters more than almost anything else here.
- Your income stability — lenders factor this into how much flexibility they’re willing to offer.
- Current market rates — if broader interest rates have fallen since you took your loan, that context can support your request.
- Your relationship with the lender — a longer or broader relationship (multiple products, consistent history) can sometimes help.
Learning how to negotiate lower loan interest rate can help borrowers reduce repayment pressure while keeping their account current. Be realistic going in: a lower rate is not a guaranteed outcome. But asking rarely costs you anything, and the cases where it works can genuinely reduce what you pay over the life of the loan.
Step 1 — Check Your Current Interest Rate
Before you approach your lender, get a clear picture of exactly where you stand:
- Your current interest rate
- Your outstanding principal
- Your remaining tenure
- Your current EMI amount
- The total remaining interest you’d pay if nothing changes
- Whether your rate is fixed or floating, if that distinction applies to your loan
Walking into a negotiation without these numbers puts you at a real disadvantage — you need to know your own position before you can make a case for changing it.
Step 2 — Build Your Negotiation Case
A few things can genuinely strengthen your request:
- A good repayment history — consistent, on-time payments are your strongest asset here.
- An improved credit profile since you took the loan, if your score has gone up.
- Stable income, especially if it’s improved since the loan was originally approved.
- Increased income since taking the loan, which reduces the lender’s perceived risk.
- Competing offers from other lenders, if you genuinely have one — this can be a meaningful point of leverage.
- A longer relationship with the bank, particularly if you hold other products with them.
The stronger and more specific your case, the more seriously it’s likely to be considered.
Step 3 — Compare Current Market Offers
Before reaching out, it’s worth researching what comparable loans are currently being offered at, so you understand where your rate sits relative to the market. This gives your request real context rather than a vague sense that “rates should be lower.”
One important caution: only reference a competing offer if you genuinely have one. Vaguely asserting that “another bank offers a lower rate” without a real, specific offer in hand is unlikely to carry much weight — and could undermine your credibility if you’re asked for details.
Step 4 — Ask the Lender the Right Questions
How you frame the conversation matters. A few phrases that tend to open a constructive discussion:
- “My repayment history has been consistent. Is there an option to review my current interest rate?”
- “Are there any rate-reduction or repricing options available for my loan?”
- “Would my current credit profile qualify me for a lower rate?”
- “If I refinance or transfer the loan, what would my effective cost be compared with staying with you?”
These questions put the ball in the lender’s court to explain what’s actually available, rather than you guessing or demanding a specific number upfront.
Step 5 — Compare Rate Reduction vs EMI Reduction
It’s worth understanding that these are two different things, and conflating them can lead to a worse outcome than you intended:
- A lower interest rate generally means you pay less in total interest over the remaining tenure — this is usually the better outcome if you can manage your current EMI amount.
- A longer tenure can lower your monthly EMI, but it often means paying more total interest over the life of the loan, since you’re spreading repayment over more months.
If your main concern is the size of your monthly payment, a longer tenure might feel like relief — but it’s worth understanding that this can increase what you pay overall, even if the interest rate itself doesn’t change.
Step 6 — Consider Loan Transfer or Refinancing Carefully
If your current lender isn’t able to offer a better rate, transferring or refinancing your loan elsewhere is sometimes an option — but it needs careful evaluation, not just a comparison of headline rates:
- A potentially lower interest rate elsewhere
- Processing fees for the new loan
- Transfer or foreclosure charges from your existing lender, where applicable
- Documentation costs
- The new loan’s overall terms
- The total cost of switching, not just the monthly saving
The number that actually matters here is the effective overall cost of switching — factoring in every fee involved — not just the advertised interest rate on the new offer. A lower rate that comes with high transfer and processing costs may not actually save you money, especially if your remaining tenure is short.
What If the Bank Says No?
A declined request isn’t necessarily the end of the conversation. A few alternatives worth exploring:
- Ask about tenure modification as a separate option from a rate change.
- Ask about repayment restructuring options, particularly if your financial situation has genuinely shifted.
- Compare refinancing with another lender, if the numbers work out after fees.
- Review your monthly budget to see if there’s room to manage the current EMI more comfortably.
- Reduce discretionary expenses where possible, to ease the pressure without changing the loan itself.
- Contact the lender again if your circumstances change — a “no” today doesn’t necessarily mean “no” permanently, especially if your credit profile improves or market rates shift.
What You Should NOT Do
A few important cautions:
- Don’t intentionally miss an EMI to gain negotiating leverage. This damages your credit report and repayment history — exactly the things that give you leverage in the first place.
- Don’t take another expensive loan without calculating the total cost. A lower advertised rate isn’t automatically a better deal once fees are included.
- Don’t focus only on your EMI while ignoring total interest. A smaller monthly payment can still mean paying more overall.
- Don’t accept a lower rate without checking associated fees. Processing charges or other costs can offset the benefit.
- Don’t wait until multiple EMIs are overdue before contacting the lender. The earlier you reach out, the more options are typically available to you.
Example — How a Small Rate Reduction Can Matter
Here’s a simple, illustrative example — actual figures will vary based on your loan’s specific amortisation schedule and lender terms:
Say you have an outstanding principal of ₹5,00,000, with 36 months remaining, currently at a 14% annual interest rate.
- At 14%: your EMI is roughly ₹17,090, and the total interest paid over the remaining tenure is roughly ₹1,15,300.
- At a negotiated 12%: your EMI drops to roughly ₹16,610, and the total interest paid over the remaining tenure is roughly ₹97,800.
That’s a monthly saving of around ₹480, and a total interest saving of roughly ₹17,500 over the remaining tenure — from a 2-percentage-point rate reduction alone. This is purely illustrative; your actual savings will depend on your specific principal, tenure, and how your lender structures the reduction.
Pre-Default Loan Negotiation Checklist
- Check your current interest rate
- Check your outstanding principal
- Review your credit report
- Check your repayment history
- Research comparable market rates
- Calculate your potential savings
- Compare refinancing costs, if considering that route
- Contact the lender before missing an EMI
- Get any revised terms in writing
Frequently Asked Questions
If you want to negotiate lower loan interest rate, contact your lender before missing an EMI.
Can I negotiate my loan interest rate with my bank?
In many cases, yes, particularly if you have a consistent repayment history and a strong credit profile. It’s not guaranteed, but it’s worth asking, especially before your account runs into any payment trouble.
How can I ask my bank to reduce my interest rate?
Reach out proactively, reference your repayment history and credit profile, and ask directly whether a rate review or repricing option is available for your loan.
Can a good CIBIL score help me negotiate a lower rate?
Yes, generally. A strong credit score signals lower risk to the lender and can support your case for a reduced rate.
Can reducing the interest rate reduce my EMI?
Yes, a lower interest rate typically reduces your EMI, assuming your tenure stays the same.
Should I refinance my loan if another lender offers a lower rate?
It’s worth evaluating, but compare the effective total cost — including processing, transfer, and foreclosure fees — rather than just the headline interest rate.
Is reducing EMI the same as reducing total interest?
No. A lower EMI achieved by extending your tenure can actually increase the total interest you pay over the life of the loan, even if the rate itself doesn’t change.
Can I negotiate a lower interest rate after taking a personal loan?
In some cases, yes, though flexibility varies by lender and loan type. It’s generally easier if your repayment history and credit profile have improved since you took the loan.
Should I stop paying my EMI to negotiate with the lender?
No. Missing payments damages your repayment record and credit score — the exact things that give you leverage in a negotiation. Reach out while you’re still current, not after you’ve defaulted.
If your EMIs are starting to feel like a strain, the best time to act is now — before it becomes a bigger problem. Getting a clear, honest look at your options can help you decide whether negotiation, restructuring, or something else is the right next step.
👉 Get a free debt assessment with TrueSettle to understand your options before you’re under pressure.
👉 Explore your repayment options and find the approach that fits your situation.